New Update: Rising Oil Costs are Affecting Retirement Plans. Will you be impacted?
Understanding the Impact of High Inflation: Insights for Sonoco Products Employees and Retirees



Barron’s: Awarded on 9/12/2025 (Mega RIA) for 6/30/24-6/30/25. Paid for logo use. Forbes: Awarded 10/1/25 for 3/31/24-3/31/25. Paid for logo use. USA Today: Awarded 4/15/26 for the five-year period ending January 2026. Paid for logo use.
Oil prices between $50 and $120 per barrel with 80% annualized volatility have created ripple effects throughout the economy over the past six months. Oil price volatility ripples through the broader economy by influencing inflation expectations, interest rates, and equity market valuations. For employees at Sonoco Products, energy sector holdings within retirement accounts, such as oil stocks in a 401(k), can experience significant price swings that affect portfolio allocation; if sold during downturns, realized losses or gains may create unexpected tax consequences. For Sonoco Products employees building retirement savings, oil-driven inflation and market volatility make disciplined saving and diversified allocation more important, as energy cycles can disrupt both portfolio values and purchasing power. Consulting with a financial advisor can help you understand how energy conditions affect your specific situation and build a plan that adapts accordingly.
In March 2022, the Consumer Price Index for All Urban Consumers (CPI-U), the most common measure of inflation, rose at an annual rate of 8.5%, the highest level since December 1981.
1
It's not surprising that a Gallup poll at the end of March found that one out of six Americans considers inflation to be the most important problem facing the United States.
2
When inflation began rising in the spring of 2021, many economists, including policymakers at the Federal Reserve, believed the increase would be transitory and subside over a period of months. The inflation surge ultimately proved more stubborn than expected. It is helpful to understand the forces behind those rising prices, the Fed's response to combat them, and how the situation ultimately resolved.
Hot Economy Meets Russia and China
The fundamental cause of rising inflation continues to be the growing pains of a rapidly opening economy — a combination of pent-up consumer demand, supply-chain slowdowns, and not enough workers to fill open jobs. Loose Federal Reserve monetary policies and billions of dollars in government stimulus helped prevent a deeper recession but added fuel to the fire when the economy reopened.
The Russian invasion of Ukraine placed additional upward pressure on already high global fuel and food prices.
3
At the same time, a COVID resurgence in China led to strict lockdowns that closed factories and tightened already struggling supply chains for Chinese goods. The volume of cargo handled by the port of Shanghai, the world's busiest port, dropped by an estimated 40% in early April.
4
Behind the Headlines
Although the 8.5% year-over-year 'headline' inflation in March 2022 was a striking number for clients to consider at the time, monthly numbers provided a clearer picture of the trend. The month-over-month increase of 1.2% was extremely high, but more than half of it was due to gasoline prices, which rose 18.3% in March alone. 5 Despite the Russia-Ukraine conflict and increased seasonal demand, U.S. gas prices dropped in April, but the trend was moving upward by the end of the month. 6 The federal government's decision to release one million barrels of oil per day from the Strategic Petroleum Reserve for the next six months and allow summer sales of higher-ethanol gasoline may help moderate prices. 7
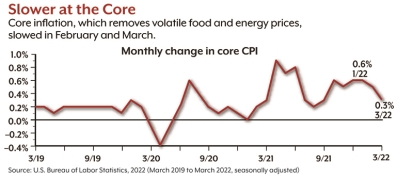
Core inflation, which strips out volatile food and energy prices, rose 6.5% year-over-year in March, the highest rate since 1982. However, it's important that our Sonoco Products clients consider that the month-over-month increase from February to March was just 0.3%, the slowest pace in six months. Another positive sign was the price of used cars and trucks, which rose more than 35% over the last 12 months (a prime driver of general inflation) but dropped 3.8% in March.
8
Wages and Consumer Demand
In March, average hourly earnings increased by 5.6% — but not enough to keep up with inflation and blunt the effects that impacted a variety of businesses, as well as many Sonoco Products employees and retirees around the country. Lower-paid service workers received higher increases, with wages jumping by almost 15% for non-management employees in the leisure and hospitality industry. Although inflation cut deeply into wage gains over the prior year, wages have increased at about the same rate as inflation over the two-year period of the pandemic. 9
One of the central questions at the time was whether rising wages would enable consumers to continue to pay higher prices, which can lead to an inflationary spiral of ever-increasing wages and prices. Signals were mixed: consumer spending rose 1.1% in March 2022, but an early April 2022 poll found that two out of three Americans had already cut back on spending due to inflation.
10-11
Soft or Hard Landing?
The inflationary situation raised many questions about the path forward. The Federal Open Market Committee (FOMC) of the Federal Reserve laid out a plan to fight inflation by raising interest rates and tightening the money supply. After dropping the benchmark federal funds rate to near zero to stimulate the economy at the onset of the pandemic, the FOMC raised the rate by 0.25% at its March 2022 meeting and projected the equivalent of six more quarter-percent increases by the end of 2022 and three or four more in 2023.
12
That path was projected to bring the rate to around 2.75%, just above what the FOMC considered a 'neutral rate' that would neither stimulate nor restrain the economy.
13
That same shift from growing assets to drawing them down applies directly to the pension decisions in front of you at Sonoco Products. Sonoco Products maintains an active defined benefit pension plan, meaning eligible employees continue to accrue benefits based on years of service and compensation. If you are eligible for a lump sum payout, IRS Section 417(e) segment rates determine how the future annuity stream converts to a present-value payment - rising rates compress the lump sum, so monitoring the plan's stability period and lookback month is critical before you lock in your election date. The choice between a single-life annuity, a joint-and-survivor option, or a lump sum (where available) is generally irrevocable once made, and timing that decision relative to interest rate conditions can meaningfully affect your retirement income picture.
On the healthcare side, Sonoco Products provides continued medical coverage to eligible retirees, which can bridge the gap between retirement and Medicare eligibility at age 65 or serve as a supplement to Medicare thereafter. Confirming the service and age requirements for retiree coverage, and understanding your premium contribution, is an important step in building an accurate healthcare cost projection. Coordinating Sonoco Products's retiree coverage with Medicare Part B and Part D enrollment timing can also reduce duplication and avoid late-enrollment penalties. Connecting your specific Sonoco Products benefits situation to a comprehensive retirement income plan - and understanding how each component interacts - gives you the most complete picture of what retirement will look like.
Those rate increases successfully brought the Fed's preferred measure of inflation, the Personal Consumption Expenditures (PCE) Price Index, down toward the Fed's 2% target -- a gradual disinflation that played out through 2023 and 2024.
14
PCE inflation -- which had reached 6.6% in March 2022 -- tends to run below CPI; as the Fed's tightening took hold, both measures declined meaningfully through 2023 and 2024.
15
The FOMC went on to raise the fund's rate by 0.5% at its May 2022 meeting -- the first half-percent increase since May 2000 -- and continued hiking aggressively through 2022 and into 2023. The FOMC also reduced the Fed's bond holdings to tighten the money supply.
16
The question facing the FOMC is how fast it can raise interest rates and tighten the money supply while maintaining optimal employment and economic growth. The ideal is a 'soft landing,' similar to what occurred in the 1990s, when inflation was tamed without damaging the economy. At the other extreme is the 'hard landing' of the early 1980s, when the Fed raised the fund's rate to almost 20% in order to control runaway double-digit inflation, throwing the economy into a recession. 18
Fed Chair Jerome Powell acknowledges that a soft landing will be difficult to achieve, but he believes the strong job market may help the economy withstand aggressive monetary policies. Supply chains are expected to improve over time, and workers who have not yet returned to the labor force might fill open jobs without increasing wage and price pressures. 19
March 2022 did in fact represent the peak of that inflationary surge. Inflation trended lower through 2023 and 2024, though the descent was gradual. Employees and retirees are encouraged to revisit their financial plans in light of the current interest rate environment.
We'd like to remind our clients from Sonoco Products that projections are based on current conditions, are subject to change, and may not come to pass.
1, 5, 8-9) U.S. Bureau of Labor Statistics, 2022
2) Gallup, March 29, 2022
3, 7) The New York Times, April 12, 2022
4) CNBC, April 7, 2022
6) AAA, April 25 & 29, 2022
10, 15) U.S. Bureau of Economic Analysis, 2022
11) CBS News, April 11, 2022
12, 14, 16) Federal Reserve, 2022
13, 17) The Wall Street Journal, April 18, 2022
18) The New York Times, March 21, 2022
In the context of the retirement benefits provided by Sonoco Products Company, what are the different scenarios that could lead an employee to choose either the Normal Retirement Benefit or the Early Retirement Benefit, and what factors should be considered in making this decision? Additionally, how do these benefits interact with the vesting service and benefit service calculations specified by Sonoco Products Company?
Normal Retirement Benefit: Available at age 65, provides full monthly pension calculated by a predetermined formula. Early Retirement Benefit: Available from age 55 with 15 years of service, but monthly payments are reduced to account for the longer payment period. Employees must weigh the reduction in monthly benefits against the potential need or desire to retire early. Considerations: The choice largely depends on personal financial needs, health status, and employment circumstances. Early retirement reduces monthly benefits, which could impact long-term financial stability.
Considering the details about tax implications in the Sonoco Pension Plan, what steps should employees take to ensure they understand the taxation of both monthly annuity payments and lump sum payments when they retire from Sonoco Products Company? What resources does Sonoco offer to assist employees in navigating these tax obligations effectively?
Monthly Annuity Payments: Subject to federal income tax; state and local taxes may also apply. Employees can choose whether or not to have taxes withheld. Lump Sum Payments: Subject to mandatory 20% federal withholding if not rolled over into another qualified plan. Employees must consult with tax professionals to understand the taxation and potential penalties, especially if under age 59½. Resources: Sonoco provides access to benefits specialists through their Benefits Center and recommends consultation with tax advisors to manage tax obligations effectively.
How does Sonoco Products Company define and calculate the "Maximum Plan Benefit," and what impact do IRS limits have on the benefits that employees may receive upon retirement? Furthermore, how does this ensure that employees understand their entitlements under the plan?
Defined by IRS limits, which cap the annual benefits an employee can receive. For 2018, the limit was $220,000. Impact: Ensures high earners are aware of the maximum pension they can draw annually, and helps in planning additional retirement savings if necessary.
For employees at Sonoco Products Company who may be considering reemployment after retirement, what are the potential impacts on their pension benefits, and what guidelines does the company provide regarding how these benefits are recalculated upon re-entering the workforce?
Pension benefits cease during reemployment and resume upon re-retirement, recalculated based on additional service. This could affect decisions on returning to work post-retirement. Guidelines: Sonoco outlines how benefits are recalculated and emphasizes consulting with the Benefits Center to understand the specific impacts.
In what ways can employees of Sonoco Products Company calculate their required service years to determine pension eligibility, and what nuances exist in the vesting and benefit service calculations? How do these calculations affect the retirement planning process for long-term employees?
Vesting Service: Determines eligibility for a pension. A minimum of five years is required for a vested pension benefit. Benefit Service: Used to calculate the amount of pension. It includes periods of employment but may exclude certain leaves or breaks in service. Implications: Understanding these definitions helps employees plan their career and retirement timing to maximize benefits.
Employees at Sonoco Products Company are often curious about the various forms of payment they can choose for their pension. What are the available options, and how do these options differ in terms of financial implications for the retiree and their beneficiaries?
Options: Single life annuity, joint and survivor annuities (50%, 75%, 100% survivor benefits). Financial Implications: Each option impacts the monthly benefit amount and the security it provides to beneficiaries, necessitating careful consideration based on marital status and financial needs.
Understanding the process of applying for plan benefits can be complex for many employees. What are the specific steps that Sonoco Products Company employees need to follow to apply for their pension benefits, and what resources are available to help streamline this process?
Process: Initiated via Sonoco Benefits Center, involving choosing a retirement date, understanding benefit options, and completing necessary paperwork. Resources: Detailed support through retirement specialists aids in navigating the process smoothly.
Many employees may not be aware of their rights under ERISA as participants in the Sonoco Pension Plan. What specific rights and protections do employees have, and how can they assert these rights if there are disputes or issues regarding their pension benefits at Sonoco Products Company?
Provides specific rights regarding plan information, appeal processes for denied claims, and protections against plan abuses. Asserting Rights: Outlines steps to take if there are disputes over pension benefits, including the right to sue after exhausting administrative remedies.
If a Sonoco Products Company employee experiences a significant life change, such as divorce or a domestic relations order, what procedures must they follow regarding their pension benefits, and how does Sonoco manage such situations under the guidelines laid out in the plan documentation?
Procedures: Employees must follow specific procedures for dividing pension benefits in the event of divorce, under a Qualified Domestic Relations Order (QDRO). Management: Sonoco’s Benefits Center provides guidance and necessary documentation to ensure compliance with legal requirements.
For employees looking to learn more about their retirement options and benefits at Sonoco Products Company, what contact information is available for them to reach out for assistance? How can employees utilize these resources effectively to gain a clearer understanding of their retirement planning?
Available through the Sonoco Benefits Center, offering comprehensive support for retirement planning and benefit queries, essential for effective retirement planning.

For more information you can reach the plan administrator for Sonoco Products at , ; or by calling them at .
Help shape our next stories
Choose the topics you’d love to read more about. Your input helps us focus on content that matters to you.