2027 Tax Rates & Inflation
Each year the IRS adjusts tax brackets, deductions and retirement plan limits for inflation. These are the 2027 changes most likely to matter to employees who are approaching retirement:
The personal exemption remains at $0. The One, Big, Beautiful Bill Act made that change permanent.
Retirement account contributions: Pre-tax contributions to your employer's 401(k) plan may help reduce your taxable income. For 2027, employees can contribute up to $25,500 to 401(k), 403(b) and most 457 plans. Employees age 50 and over can add a catch-up contribution of up to $8,500, and employees age 60 through 63 may be able to make a higher catch-up of up to $11,750 if their plan allows it. If your 2026 Social Security wages from the employer sponsoring your plan were above $155,000, any 2027 catch-up contributions must be made as Roth (after-tax) contributions. The IRA contribution limit for 2027 is $7,500, plus a catch-up amount for those age 50 and over.
Charitable deduction for non-itemizers: Beginning with tax year 2026, taxpayers who take the standard deduction may deduct up to $1,000 ($2,000 joint) of cash gifts to eligible charities. Gifts to donor-advised funds and non-cash gifts do not qualify.
Child Tax Credit: For 2027, the Child Tax Credit is up to $2,300 per qualifying child. The credit begins to phase out above $200,000 ($400,000 joint) of modified adjusted gross income.
Remote work and state taxes: If you work remotely in a different state from your employer's office, you may owe tax in more than one state. Some states, including New York, apply a "convenience of the employer" rule that can tax a remote employee's wages as if the work were done in that state. A tax advisor can help you review whether credits or other options apply to your situation.
2027 Federal Income Tax Brackets
| Rate | Single | Married Filing Jointly | Married Filing Separately | Head of Household |
|---|---|---|---|---|
| 10% | $0 - $12,800 | $0 - $25,600 | $0 - $12,800 | $0 - $18,250 |
| 12% | $12,801 - $52,025 | $25,601 - $104,050 | $12,801 - $52,025 | $18,251 - $69,650 |
| 22% | $52,026 - $109,125 | $104,051 - $218,250 | $52,026 - $109,125 | $69,651 - $109,100 |
| 24% | $109,126 - $208,325 | $218,251 - $416,650 | $109,126 - $208,325 | $109,101 - $208,300 |
| 32% | $208,326 - $264,550 | $416,651 - $529,100 | $208,326 - $264,550 | $208,301 - $264,550 |
| 35% | $264,551 - $661,375 | $529,101 - $793,650 | $264,551 - $396,825 | $264,551 - $661,350 |
| 37% | $661,376+ | $793,651+ | $396,826+ | $661,351+ |
Source: IRS Rev. Proc. 2026-35, section 3.01, Tables 1-4 (IR-2026-133, November 5, 2026).
Inflation reduces purchasing power over time, so the same goods and services cost more as prices rise. Social Security benefits rise 3.6% in January 2027 through the annual cost-of-living adjustment. When building a retirement income plan, consider inflation assumptions, Medicare premiums, prescription drug costs and other health care expenses alongside the 2027 tax brackets and deductions above. For 2027, the standard Medicare Part B premium is $209.40 a month and the annual deductible is $292. The Part A inpatient hospital deductible is $1,776 per benefit period. Hospital coinsurance is $444 a day for days 61 through 90 and $888 a day for lifetime reserve days. Skilled nursing facility coinsurance is $222 a day for days 21 through 100. Out-of-pocket spending on covered Part D drugs is capped at $2,400.
Sources: IRS, Social Security Administration, Centers for Medicare & Medicaid Services.
Please choose a date that works for you from the available dates highlighted on the calendar.
No matter where you stand in the planning process, we hope this guide provides you with a good overview of the steps to take and resources available to help simplify your transition from your employer into retirement and get the most from your benefits in your city, your state.
You know you need to be saving and investing, especially since time is on your side the sooner you start, but you may not have the time or expertise to know if you’re building retirement savings that can last after leaving your company. We can help.
Source: Is it Worth the Money to Hire a Financial Advisor? The Balance, 2021
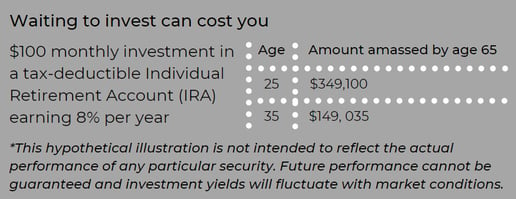
Starting to save as early as possible matters. Time on your side means compounding can have significant impacts on your future savings. And, once you’ve started, continuing to increase and make the most of your contributions for your 401k plan is key.
*Source: Reference Point 2025, T. Rowe Price, April 2025
As decades go by, you’re likely full swing into your career at your employer, and your income probably reflects that. However, the challenges of saving for retirement start coming from large competing expenses: a mortgage, raising children in your city, your state, and saving for their college.
One of the classic planning conflicts is saving for retirement versus saving for college. Most financial planners will tell you that retirement from your company should be your top priority because your child can usually find support from financial aid while you’ll be on your own to fund your retirement once you reach retirement age.
The amount you'll need to invest towards your retirement is always based on your unique financial situation and goals. However, a good rule of thumb is to consider investing at least 10% of your salary toward retirement throughout your 30s and 40s.
As you enter your 50s and 60s, you’re ideally at your peak earning years with some of your major expenses, such as a mortgage or child-rearing, behind you. This can be a good time to consider whether you have the ability to boost your retirement savings goal to 20% or more of your income. For many people, this could potentially be the last opportunity to stash away funds.
In 2027, workers can contribute up to $25,500 into their retirement plan/401(k), and workers age 50 or older can add an additional $8,500 in catch-up contributions, for a combined total of $34,000 for the year. For those aged 60 - 63 during 2027, the catch-up provision is $11,750. These limits are adjusted annually for inflation.
These retirement savings vehicles give you the chance to take advantage of three main benefits:
Disclaimer: This employer operates in nine different states. Although there are many similarities among the various pensions, each state will have slight differences as well. Even within a state like California, there are regional differences among the pensions available in Northern CA, Central CA, and Southern CA.
To help you understand the pensions at a high level, including common terms used and examples of the pension formulas, here we review several pensions, including the Medical Group Plan, the Employee Pension Plan, the Salaried Retirement Plan, and the Southern California Medical Group Plan.
Retirement and Savings Plans
Pension Plan (Plan 1)
Your Pension Plan (Plan 1) is a defined benefit plan that pays a monthly benefit amount to you at retirement based upon the formula described on the right.
Membership and Vesting Service
You will automatically become a member of Plan 1 effective your first employment anniversary date, provided you completed 1,000 hours of vesting service during that year. You will vest in the plan after completion of five years of vesting service (a calendar year in which you were compensated 1,000 hours or more).
Retirement Age and Years of Service
Normal retirement is age 65, however, a reduced benefit may be received earlier, if eligible. A physician with 30 years of credited service at age 65 would be entitled to 50% of their highest average compensation.
Highest Average Compensation (HAC)
Retirement income is calculated based on your HAC, which is the 36 highest paid consecutive months with the Medical Group over your entire service period and includes both base pay and annual incentive payment multiplied by your years of credited service.
Full Early Retirement Plan
The Full Early Retirement Plan gives you the option to begin receiving benefits as early as age 60 without actuarial reduction for payment before age 65. To be eligible for this plan, you must be at least age 60 and have completed 15 years or more of vesting service before your retirement date in your city, your state.*
*If you were hired or rehired on or after July 1, 2012, qualifying for the Full Early Retirement Plan also requires at least five years of vesting service as a Medical Group physician after that hire or rehire date, completed immediately before you separate from service.
Credited Service
Credited service begins on your date of hire and is based on 2,000 hours of compensated service each calendar year. Proportional credited service is granted for years in which compensated service is less than 2,000 hours.
Benefit Formula
2% of Highest Average Compensation (HAC) per year during first 20 years of credited service, and 1% per year thereafter.
Payment Options
Life annuity, joint and survivor annuity, period certain, or installments.

Contribution Plan (Plan 2)
The Medical Group contributes to Plan 2 based upon your eligible compensation (base compensation plus bonus) each pay period. Plan 2 contributions are equal to 5% of the amount of eligible compensation you receive, up to the Social Security Wage Base (SSWB), plus 10% of your eligible compensation over the SSWB up to the maximum IRS compensation limit.
For 2027, the SSWB limit is $192,300. The limit on the amount of compensation that can be taken into account when determining contributions and benefits in retirement plans is $375,000 for calendar year 2027.
Plan 2 contributions begin the first of the month following the completion of 1,000 hours of service within an anniversary year.
Salary Deferral Plan 401k (Plan 3)
Your 401k contributions can be made on a pre-tax or Roth (post-tax) basis. You choose how you want to invest your savings.
Contributions are subject to annual IRS and other limits, as shown in the table below.
Contributions can begin the first of the month following your date of hire. If you do not make an election within 30 days of your hire date, you will be automatically enrolled at an employee pre-tax contribution rate of 6%. If you were automatically enrolled at 6% and do not make a change, your contribution percentage will increase by 1% on your anniversary date each year up to a maximum of 15%.


Medical Group (physicians) Pension Plan 2 (2027 maximum)
Plan 2 maximum annual contribution (2027)
| Plan 2 | 5% | 10% | Total |
|---|---|---|---|
| 2027 Social Security Wage Base ($192,300); IRC compensation limit ($375,000) | $9,615 | $18,270 | $27,885 |
5% of eligible pay up to the Social Security Wage Base plus 10% of eligible pay above it, up to the IRS compensation limit. Sources: SSA 2026 COLA fact sheet; IRS Notice 2025-67.
Sample Pension Calculations
Medical Group (Salaried Employees)

(Nurses and other applicable work groups)
Defined Benefit Pension
Overview
The pension benefit is based on a formula using an average of your hourly wage rate, your length of credited service, a pension multiplier, and your age at retirement in your state.
A year of service is defined as 1,000 paid hours in a calendar year, prorated for less than 1,000 hours (depending on your group), and includes all employer paid hours in any job classification, in any region.
Requires vesting: the plan is fully vested after five years of service. After vesting, you are entitled to the future benefit payment, even if you leave your employer before your normal or early retirement age.
The normal retirement age is 65, although there is an early retirement option at age 55 if you have completed a minimum of 15 years of service (depending on your group).
Breaks in service are allowed, but will require you to track your multiple periods of employment.
Additionally, a maximum of 1,000 hours of Workers’ Compensation Leave of Absence (WCLOA) taken on or after 10/1/2000 may count toward years of service for retirement and post-retirement benefit eligibility. WCLOA hours do not count as credited service or toward eligibility for any other benefits.
This benefit is available as either multiple forms of annuity payments or as a lump sum payout.
Keys to Better Understanding
A defined benefit pension is a "promise" of receiving a defined payment amount, using an established formula. You know what you are owed in a pension payment at all times.
There is no cost to the participating employee. All funding costs are paid by your employer. Additionally, your employer assumes all the risks in funding the plan and investing the pension trust assets.
Pension Benefit Guaranty Corporation (PBGC) insures the plan's annuity benefits.
Pension plan year is a calendar year.
Year of service is determined by paid hours, not worked hours or passage of time.
Years of service are for vesting and eligibility purposes only: Do you have five years and are vested? Do you have 15 years and are therefore eligible to retire early?
Both the retiree medical benefit and the Health Reimbursement Account (HRA) use pension years of service as a qualifying measure.
Defined Benefit Pension
How the pension benefit is calculated (depending on your group, see chart below):
A pension benefit multiplier of 1.45% is used. The multiplier defines income replaced by the pension payment.
Year of credited service is defined as 1,800 paid hours in a calendar year.
Partial years of credited service are also included for calendar years with less than 1,800 paid hours.
For all calendar years prior to 2003, one year of credited service
was 2,000 paid hours.
Final Average Monthly Compensation (FAMC) is calculated by averaging your highest hourly wage rates taken over a consecutive 60 month period from your last 120 months of employment. Typically the average will be over your last five years of employment given how wage grids are constructed.
The 60-month average uses your base hourly rate only, no
ACP/per diem/other differentials apply.
Multiplying your 60-month average rate by 173.3 hours equals your
FAMC. 173.3 is the average number of hours a full-time employee
is paid per month (2,080 hours/12months).

Final Average Monthly Compensation
multiplied by
Years of credited service
multiplied by
Pension benefit multiplier


Defined Benefit Pension Plan (Common Plan)
This plan is offered to physicians and corporate officers only.
There are two types of service that affect the Common Plan:
• Qualifying Service = at least 10 years (part-time / full time)
• Credited Service is time counted to determine the amount of retirement income. It is generally calculated the same as Qualifying Service, but is prorated to work schedule. For example, if you work an 8/10ths work schedule for 10 years, you would have 10 years of Qualifying Service, but only 8 years of Credited Service.
In addition to Credited Service, a physician’s Highest Average Compensation (HAC) is used in the benefit calculation. HAC is the average monthly base compensation for the highest 36 consecutive months of the last 120 months as an eligible physician.
The formula to determine the Common Plan benefit amount is:
2% of HAC (up to 20 years) + 1% of HAC (over 20 years)
Example: The benefit amount for an age 65 physician with a HAC of $15,000 and 30 years of Credited Service
would be calculated as follows:
(2% x $15,000 x 20 years) + (1% x $15,000 x 10 years) = $7,500 per month*
* The benefit amount of the payment will be actuarially adjusted if you begin payment before or after age 65 and/or select a payment option other than lifetime monthly payments.
Southern California Medical Group Physicians’ 401k Plan
Eligibility is six months of service. Per diem counts towards this enrollment period. These are contributions that you self-direct within the investment options available in your plan as either pre-tax or post-tax (Roth).
Under the 401(k) Plan for Permanente Medical Groups' 2023 Summary Plan Description, a distribution taken before age 59 1/2 is not subject to the additional 10% federal early-withdrawal tax when it is made on account of your termination of service with the Medical Group at or after age 55.
Southern California Medical Group Keogh Plan
Upon attaining Partnership, physicians are eligible to contribute to the Keogh Plan. This plan allows Partners to make tax-deductible contributions to a retirement plan which accrues tax-deferred earnings until distributed from the plan upon retirement from the Partnership.
Even though your contributions do not begin until you attain Partnership, you must elect to participate (or not participate) in the Keogh Plan within 180 days from your date of hire. Any service time attained as a Per Diem applies towards this enrollment period.
Electing to participate in the Keogh Plan is an irrevocable commitment to make an annual contribution of the amount required for the selected level of participation. You will receive only one opportunity to make an election to participate. If you elect to not participate by your 180th day of employment, you will not be able to commence participation at a later date.
If you elect to participate in the Keogh Plan, you may select from four contribution levels: 100%, 70%, 50%, or 25%. Changes in the contribution level or participation status are not permitted once an election has been made. At the end of each year, an actuarial firm determines the next year’s contribution limit. A physician’s participation level dictates the percentage of the annual contribution limit that the physician will contribute.
The IRS sets an annual limit for combined contributions to a defined contribution plan. In other words, there is a limit on your combined TSR-401k and Keogh contributions.
Early Separation Program (ESP)
This program allows Partners between the ages of 58 and 65 an opportunity to retire early and receive a temporary annuity until the normal retirement age of 65. ESP requires one year of advance approval by the Southern California Medical Group Board of Directors.
Securing Your Future
Part 1: Tax Sheltered Annuity (TSA) Plan or Medical Group 401(k) Plan
Save for retirement through pre-tax or Roth after-tax contributions, or both. You choose investment options for your savings.
You’re enrolled automatically at a 2% contribution unless you opt out. Your contribution increases by 1% per year up to 6%, unless you opt out.
You’re immediately 100% vested in your contributions to your account.
The Medical Group 401(k) Plan is for Southern California Medical Group employees. The TSA is for health plan and hospital employees.
Part 2: Supplemental Savings and Retirement Plan
After two years of service, your employer has contributed 5% of base salary to this plan for eligible employees. The plan was amended to end participation for certain non-union, non-executive employees in 2025, so check your latest statement to see whether contributions continue. You can also make after-tax contributions and choose your investment options. You’re immediately 100% vested in contributions to your account.
Part 3: Retirement Plan
This defined benefit pension plan provides retirement income based on your compensation and years of service when you retire. Your employer makes all contributions to this plan. You are vested in the plan after five years of service.
Retiree Benefits
You may be eligible for retiree health benefits when you retire, depending on your age and years of service at retirement.
Life and Accident Insurance
This insurance can help provide for your loved ones in the event of a serious injury or death. Some of these benefits are optional, and others are included at no cost to you:
Employee Life Insurance - coverage of two times your annual salary or a maximum of $50,000, at no cost to you.
Optional Life Insurance - coverage of up to $1 million.
Dependent Life Insurance - coverage of up to $100,000 for your spouse or domestic partner, and up to $10,000 for eligible children.
Accidental Death and Dismemberment - coverage for yourself of up to $350,000, and coverage for your spouse or domestic partner and children. Cost depends on the options you choose.
Business Travel Accident - coverage provided at no cost to you.
Survivor Assistance - one times your monthly base salary, at no cost to you.
Disability Income
Disability benefits provide income in the event you’re unable to work for an extended period because of a serious illness or injury.
Hospital Employees (Southern CA) Example

There are three parts to the Northern California hospital plan. This is for salaried non-union employees at your employer, which includes pharmacists.
Part 1: Tax Sheltered Annuity Plan (TSA)
This plan offers immediate eligibility. After two years of employment, you may be eligible for an employer contribution (not a match) of 2% of your salary up to the Social Security wage base and 5% of any salary above it.
Part 2: Supplemental Savings and Retirement Plan
This is a qualified plan where the employer has contributed 5% of an eligible employee's base salary after two years of service; participation ended for certain non-union, non-executive employees in 2025, so confirm on your latest statement whether you still receive this contribution. The employee can add after-tax contributions into the plan and the employer contribution is immediately vested.
Part 3: Salaried Retirement Plan
This plan is the pension (defined benefit plan) and the company contributes into the plan based on a formula of FAP (last 10 years of employment and the average of the 60 highest consecutive months) multiplied by a pension multiplier of 1.5 minus age penalties of 5% for retirement between the ages of 55-60 and 3% between the ages of 60-65.
Effective January 1, 2026, if you are vested, are not represented by a union when you leave, and leave your employer before meeting this plan's early-retirement requirements (age 55 with 15 years of service, or age plus years of service equal to at least 75), a plan amendment lets you elect an actuarially reduced benefit that starts before age 65 instead of waiting until 65.
Retiree Benefits
You may be eligible for retiree health and welfare benefits when you retire, if you meet certain age and years of service requirements.
Other Benefits
Employee Assistance Program
This program provides free and confidential counseling for personal issues, as well as referrals for child and elder care.
Parent Medical Coverage
Your Medicare-eligible parents, step-parents, parents-in-law, or parents of your domestic partner may have an opportunity to enroll in employer medical coverage at their own expense.
Voluntary Programs
You may enroll in Benefits by Design Voluntary Programs at your own expense if you are regularly scheduled to work 20 or more hours per week. Programs offered include long-term care, term life, pet, auto, and home insurance, as well as legal services and identity theft protection.
Tuition Reimbursement
Tuition reimbursement helps you continue your education in subjects that will improve your job performance, potential for advancement, and employability. You can be reimbursed up to $3,000 per calendar year for expenses such as tuition and textbooks, including up to $500 for travel expenses.

Additional Resources
As a healthcare employee, you also have access to:
- Career and development opportunities to help you grow your skills and career, including professional development courses through your employer's learning programs.
- Opportunities to volunteer in communities that your employer serves.
- Employee discounts on entertainment, travel, child care, health and fitness programs, electronics, and more. You also receive discounts on over-the-counter medications and other products purchased from an in-network pharmacy.
- Healthy Workforce resources and tools to help you keep active, eat well, and thrive. If your region meets the Total Health Incentive Plan’s goals for employees to adopt a healthier lifestyle, you may also have a chance to earn up to $500 per year.
Pension Distribution Options
Please note: each pension varies; options listed below may not be available with your pension.
Standard Forms of Payment
If you are single: the standard form of payment is the Single Life Annuity.
If you are married: your spouse is entitled by federal law to receive benefits, so your standard form of payment is the 50% Joint and Survivor Annuity. This means you are legally required to obtain your spouse’s consent to elect other forms of payment. The consent must be in writing, notarized, and signed during the election period before your benefits begin (federal law allows up to 180 days).
Available Forms of Payment
• Lump Sum: Under this option, you receive a one-time lump sum amount. After you receive the Lump Sum
payment, there are no more payments due under the plan. The Lump Sum can be rolled over into a traditional
IRA, Roth IRA, or another employer’s qualified plan, if that plan accepts rollovers.
• Single Life Annuity: Under this option, you receive a monthly pension benefit until your death. However, all
pension payments stop when you die regardless of marital status. This is the standard form of payment if you
are not married (as defined by federal law) on your Benefit Commencement Date.
• 50%, 66 2/3%, and 75% Joint and Survivor Annuities: Under this option, you receive a reduced monthly benefit until your death. If you die before your beneficiary, 50%, 66 2/3%, or 75% (as elected by you) of the amount you receive will then be paid to your beneficiary as long as he or she lives. However, if your beneficiary dies before you, your monthly benefit will be reduced to the 50%, 66 2/3%, or 75% survivor benefit for the rest of your lifetime after your beneficiary's death. This option requires the designation of one person as your beneficiary, and after your payments begin, you cannot change your beneficiary. The 50% Joint and Survivor Annuity is the standard form of payment if you are married (as defined by federal law). If you are married, you must select this form of payment, with your spouse as your beneficiary, unless your spouse consents to a different election. Your spouse’s consent must be on the appropriate form and notarized. Once you begin receiving payments, you may not change your beneficiary. The monthly pension benefit you or your beneficiary receives under this option will be less than the monthly pension benefit under a Single Life Annuity because payments may continue after death. The actual difference depends on the percentage you elect, as well as the age difference between you and your beneficiary.
• 100% Joint and Survivor Annuity with 15-Year Guarantee Period and Pop-Up: Under this option,
you receive a reduced monthly benefit until your death. If you die before your Joint and Survivor Annuity
beneficiary, 100% of the monthly payment you received will then be paid to that beneficiary as long as he or she lives. Conversely, if your Joint and Survivor Annuity beneficiary dies first, the monthly amount payable to you will "pop up” to the Single Life Annuity monthly amount for the duration of your life. If you and your Joint and Survivor Annuity beneficiary both die before the 180 months (15 years) of guaranteed payments are made, payments equal to the 100% Joint and Survivor Annuity monthly benefit will be made to a designated beneficiary until the expiration of the guaranteed payment period. If your designated beneficiary does not survive to the end of the guaranteed payment period, the present value of the remaining payments will be paid to that beneficiary’s estate. This option requires the designation of both a Joint and Survivor Annuity beneficiary and a beneficiary for the guarantee period benefit. If you and your Joint and Survivor Annuity beneficiary die before 180 payments and there is no surviving designated beneficiary, the remaining payments will be made to your surviving spouse or domestic partner, if any. If there is no surviving spouse or domestic partner, the present value of the remaining payments will be paid to your estate.
• 5-, 10-, 15- and 20-Year Certain and Life Annuity: Under this option, you receive a monthly pension benefit
for your lifetime with payments that will be made for a period of at least 5, 10, 15, or 20 years, whichever you
select. If you die before the end of the specified period, your designated beneficiary will receive the monthly
payments for the remainder of the specified period. If your designated beneficiary dies before the end of the specified period, the present value of the remaining monthly benefits will be paid in accordance with the plan.
For example, if you elect the 10-year option and die after receiving payments for only six years, your beneficiary would receive monthly payments for the remaining four years. If you live longer than 10 years, payments will continue to you for as long as you live, but there are no payments to your beneficiary after your death. The monthly amount paid to you under this option will be less than you would receive under a Single Life Annuity because of the possibility that payments will continue after your death. The actual difference depends on your age at retirement and the length of the specified period. Unlike a Joint and Survivor Annuity, you can change your beneficiary for this form of payment after your payments begin.
• Fixed Monthly Installments: Under this option, you receive a fixed number of monthly payments, and then
all payments stop. You may elect to receive installments for 60, 120, 180, 240, or 360 months, or any months
up to 360. If you die after your payments stop because you have received the fixed number of monthly
payments, there will be no benefit paid to any beneficiary. If you die before you receive the fixed number of
monthly payments, your surviving designated beneficiary will receive monthly installments for the remainder of the fixed period.
• Level Income Annuity Option at Age 62, 65, or your Social Security Normal Retirement Age: Under
this option, you receive an increased monthly payment during your lifetime until age 62, age 65, or your Social
Security Normal Retirement Age (SSNRA), as you elect. That means it provides a reduced monthly payment for
your life to provide an approximate level retirement benefit when the reduced monthly payment is
combined with your estimated benefit from Social Security. This option is only available if your requested
Benefit Commencement Date is before the leveling age. The leveling age is the age at which the payment
decreases. The first decreased payment will be the first month following the leveling age. The plan offers the
following leveling ages: 62, 65, or SSNRA.
• 5-, 10-, 15- and 20-Year Certain and Life Annuity with Level Income Option at Age 62, 65, or your
Social Security Normal Retirement Age: Under this option, you receive an increased monthly payment
during your lifetime until age 62, age 65, or your Social Security Normal Retirement Age (SSNRA), as you elect.
Thereafter, it provides a reduced monthly payment payable for your life to provide an approximate level retirement benefit when the reduced monthly payment is combined with your estimated benefit received from Social Security. If you die during the period you elect (5, 10, 15, or 20 years), your beneficiary will receive the remaining payments until all of the specified payments have been made. This option is only available if your Benefit Commencement Date is before the leveling age. The leveling age is the age at which the payment decreases. The first decreased payment will be the first month following the leveling age. The plan offers the following leveling ages: 62, 65, or SSNRA.
Lump Sum vs. Annuity?
Retirees in your city, your state who are eligible for a pension can typically choose between ongoing annuity payments or a lump sum payout. Choosing an annuity effectively means that you would receive income payments for life, which may be appealing if you're worried about outliving your assets, or fear that market volatility could cause your other investments to underperform. Your annuity will continue as long as the pension plan stays solvent, providing steady, reliable income regardless of how long you live in retirement.
The major downside of choosing to receive a monthly pension is that benefits are often reduced following the early and untimely passing of the retiree and/or joint annuitant. In some cases, the pension ends altogether upon death. Additionally, unlike with Social Security, company pensions rarely contain a cost of living allowance (COLA). As a result, receiving a fixed dollar amount as a monthly pension payment means that sum will lose its purchasing power during the course of your retirement.
In contrast, selecting a lump sum payment provides you with the equivalent present value of your monthly pension income stream all at once. If you roll that money over into an IRA and invest it, the idea is that you could potentially achieve a higher rate of growth over time to generate the cash flow needed to make systematic withdrawals throughout your retirement years. Additionally, if a balance remains upon your death, it can go to your surviving spouse or heirs. The flip side of this equation is risk: you need to invest the funds for sufficient growth or face the danger of generating insufficient returns, or running out of money altogether.
Ultimately, the “risk” assessment that should be done to determine whether to take an annuity or lump sum from your pension plan depends on the return you would need to generate to make your lump sum replicate your annuity payments. For instance, if a modest annual return (like 1% to 2%) would create the same cash flow as your monthly pension payments, there is less risk that you will outlive the lump sum. However, if the equivalent cash flow requires a higher, riskier return, there's a chance that those returns won’t manifest and you could run out of money.
The decision you make matters. If you'd like some guidance, reach out to an advisor from The Retirement Group.
Interest Rates and Life Expectancy
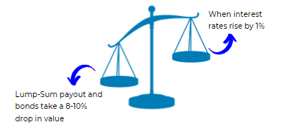
Current interest rates, as well as your life expectancy at retirement, have a large impact on lump sum payouts of defined benefit pension plans. Rising rates hurt your lump sum value. The reverse or opposite is also true. Decreasing or lower interest rates will typically increase the lump sum values.
Interest rates are important for determining your lump sum option within the pension plan. However, they have no impact on the annuity options. The Retirement Group believes all healthcare employees should have a detailed RetireKit Cash Flow Analysis comparing their lump sum value versus the monthly annuity distribution options before making their pension elections. As enticing as a lump sum may seem, the annuity for all or a portion of the pension may still be the better choice, especially in a higher interest rate environment. Every person’s situation is different, and a Cash Flow Analysis can show you how your pension choices may play out over the course of 30 or more years of retirement.
As we continue to monitor the interest rate environment, we will gain more clarity around how the year is trending. Feel free to reach out to The Retirement Group to receive help calculating and assessing your pension options in light of these shifts. We provide a complimentary Retirement Cash Flow analysis or an update to an existing one. By knowing where you stand, you can make a more prudent decision when to retire in your city, your state.
When was the last time you reviewed your 401k/TSA plan account or made any changes to it? If it’s been a while, you’re not alone. Many plan participants spend little time each year researching their 401k/TSA investment choices, and even less time making account changes.
When you retire, if you have balances in your 401k/TSA plan, you will receive a Participant Distribution Notice in the mail. This notice will show the current values that you are eligible to receive from each plan. It will also explain your distribution options and what you need to do to receive your final distribution.
Please call The Retirement Group at (800)-900-5867 for more information and to take advantage of the complimentary RetireKit Cash Flow Analysis, which will provide you with a snapshot of where you currently stand with regard to your retirement and help you plan for your retirement years in your city, your state. Are you retirement age and thinking about your future? Then contact us today.
Note: If you voluntarily terminate your employment from your employer, you may not be eligible to receive the annual contribution.
Over half of plan participants in your city, your state admit they don’t have the time, interest, or knowledge needed to manage their 401k portfolio. But the benefits of getting help go beyond convenience. A Charles Schwab study looked at plan participants who used professional 401k advice. 
Getting help can be the key to better 401k results across the board. According to the study, those who used independent professional advice:
Rolling Over Your 401k
Borrowing from your 401k
Should you? Maybe you lose your job with your employer, have a serious health emergency, or face some other issue that requires an upfront cash infusion. Banks make you jump through too many hoops for a personal loan, credit cards charge too much interest. If these are your only options, a 401k withdrawal might seem like the solution, even if it pushes off your retirement from your employer for a few years.
We understand how you feel: It’s your money, and you need it now. But take a second to see how this could adversely affect your retirement plans after leaving your employer.
Consider these facts when deciding if you should borrow from your 401k. You could:
When you qualify for a distribution from your employer-sponsored retirement plan, you typically have three options:
How does the NUA strategy work?
First, employees must be eligible for a distribution from their qualified company-sponsored plan. Generally, this means reaching retirement or age 59 1⁄2. Second, NUA only applies to company stock that has been offered as part of your 401k plan. In other words, if you have company stock that has appreciated over time, the NUA strategy may benefit you.
To leverage NUA, you would start by taking a lump sum distribution from your 401k plan, distributing your entire balance from the plan within a single tax year, after a qualifying event such as leaving your employer or reaching age 59 1/2. The portion of the plan that is made up of highly appreciated company stock is transferred to a taxable brokerage account. The remaining balance can then be rolled into an IRA for further tax deferral.
The tax benefit comes when you transfer the company stock from a tax-deferred account to a taxable account. At this time, you pay ordinary income tax only on the stock's cost basis; the net unrealized appreciation is not taxed until you sell the shares. The appreciated value of the stock above its basis is not taxed at ordinary income tax rates but at long-term capital gains rates of 0%, 15%, or 20%, depending on your taxable income. The 3.8% Net Investment Income Tax does not apply to the NUA itself, but it may apply to any growth after the distribution if your modified adjusted gross income is above $200,000 (single) or $250,000 (MFJ). Depending on your tax bracket, the difference between ordinary income and long-term capital gains rates can be significant.
You may be interested in learning more about NUA with a complimentary one-to-one session with a financial advisor from The Retirement Group.

Your retirement assets likely span several retirement accounts: IRAs, 401ks, taxable accounts, and others.
So, what is the most efficient way to take your retirement income after leaving your employer in your city, your state?
The One, Big, Beautiful Bill Act also created a new senior deduction of up to $6,000 for each taxpayer age 65 and older (tax years 2025 through 2028), available whether or not you itemize. It phases out above $75,000 of modified adjusted gross income ($150,000 for joint filers). It reduces taxable income, but it does not change how much of your Social Security benefit is taxable.
You may want to consider meeting your income needs in retirement by first drawing down taxable accounts rather than tax-deferred accounts. This may help your retirement assets last longer as they continue to potentially grow tax deferred.
You will also need to plan to take the required minimum distributions (RMDs) from any company-sponsored retirement plans and traditional or rollover IRA accounts. For those born between 1951 and 1959, RMDs begin at age 73. Under SECURE 2.0, this age is 73 for those born between 1951 and 1959, and 75 for those born in 1960 or later.
Two flexible distribution options for your IRA
When you need to draw on your IRA for income or take your RMDs, you have a few choices. Regardless of what you choose, IRA distributions are subject to income taxes and may be subject to penalties and other conditions if you’re under 59½.
Your tax advisor can help you understand distribution options, determine RMD requirements, calculate RMDs, and set up a systematic withdrawal plan.
Benefits Annual Enrollment
As stated in your employer's SPD, annual enrollment for your benefits usually occurs each fall. Before it begins, watch for enrollment materials with information about your benefit options and contribution amounts. You’ll find enrollment instructions and information about your benefit options and contribution amounts. You can keep your current coverage or select benefits that better support your needs.
Next Steps:
* Watch for your annual enrollment information in the September/November time frame.
* Review your benefits information and use the tools and resources available on your employer's Benefits Center website.
Benefits Eligibility
If you are eligible for retiree benefits, were enrolled in Optional Life Insurance before January 1, 1991, and participated in it for at least 10 consecutive years before age 65 or early retirement, you may qualify for Tapered Life Insurance. Its starting amount is the lesser of your Optional Life coverage before you retire (or reach 65, if earlier) or two times your base annual compensation, up to $1 million. This amount will continue in force for one month without reduction. Thereafter, it will taper by 1% of the original amount each month for 75 months until it reaches a minimum of 25% of the original amount. If you retire at 65 or later, tapering begins the first day of the second month after your 65th birthday; if you retire before 65, it begins the first day of the second month after you retire. Eligible retirees who do not qualify for (or decline) Tapered Life Insurance are provided Retiree Life Insurance of $50,000, paid for by the Medical Group.
If you were hired before January 1, 2021 and meet the eligibility requirements for retiree benefits, you are provided Retiree Life Insurance of $50,000 (or Tapered Life Insurance, if you qualify).
If you were hired, rehired, or transferred into an Associate physician position on or after January 1, 2021, you are generally not eligible for retiree health care or retiree life insurance benefits.
Disclaimer: This employer has many different groups of employees that are provided with similar but differing benefits. The following information pertains to the Southern California Medical Group SPD.
Retiree Medical (Medical Group)
If you were hired before January 1, 2021, you may be offered retiree medical benefits if you retire at age 55 or later with at least 15 years of service, at age 55 or later with age plus service of at least 75 (and at least 10 years of service), or at age 65 with at least 10 years of service. Physicians hired, rehired, or transferred into an Associate position on or after January 1, 2021 are generally not eligible.
If you are eligible and retire before age 65, you are offered Health Plan coverage; once you become eligible for Medicare, you must enroll in Medicare Parts A and B and the Medical Group's Medicare-coordinated retiree plan to keep coverage. Residents of your city, your state, are encouraged to review the specific coverage details applicable to their location.
The Modified Retiree Medical
If you were hired before January 1, 2021, you may be offered retiree medical benefits if you retire at age 55 or later with at least 15 years of service, at age 55 or later with age plus service of at least 75 (and at least 10 years of service), or at age 65 with at least 10 years of service. Physicians hired, rehired, or transferred into an Associate position on or after January 1, 2021 are generally not eligible.
If you are eligible, you are offered Health Plan coverage when you retire if you are under age 65; once you are eligible for Medicare, you must enroll in Medicare Parts A and B and the Medical Group's Medicare-coordinated retiree plan to keep coverage.
Employer Health Plan
Employer health plan coverage is provided to all full-time physicians and enrolled eligible spouses/domestic partners as well as dependent children (up to age 26).
Health plan coverage is comprehensive and includes basic and major medical care at network medical facilities in your city, your state. The plan covers hospitalization, surgery, maternity care, diagnostic imaging and laboratory expenses, durable medical equipment, and emergency care.
Your Health Plan Coverage Includes:
* For physicians in the Traditional Health Plan (generally available only to physicians hired before January 1, 2021; later hires are offered the HSA-qualified high-deductible health plan): $0 co-payment for doctor office visits
* $5 co-payment for each prescription
* $175 vision care allowance toward the purchase of eyeglass lenses, frames, and contact lenses every 24 months
* $0 co-payment for mental health visits, and unlimited inpatient and outpatient visits per calendar year (with a diagnosis of psychosis)
* $2,500 hearing aid allowance per device, per member, every three years
Supplemental Medical
Supplemental Medical provides additional coverage by reimbursing a percentage (100%, 80%, or 50%) of certain medically necessary expenses that are not covered by health plan coverage or that exceed plan limits.
Alternative Mental Health
Your health care benefits also include coverage for mental health services received outside of your health plan's network.
Other Benefits
Dental - You may choose to enroll in one of three dental plans: Delta Dental, United Concordia, or DeltaCare USA.
Special Dependent Coverage - You may enroll special dependents in health plan coverage.
Long-Term Care Insurance - Enrollment is closed to new applicants; physicians who already purchased a policy may continue paying premiums to keep their coverage.
Employee Assistance Program (EAP) - The Employee Assistance Program (EAP) is a free and confidential service available for active physicians and their dependent family members.
Employee Discounts - Access the online employee discounts web page to purchase discounted entertainment tickets or travel.
Short-Term & Long-Term Disability - Short-Term: Depending on where you work, you may have access to short-term disability (STD) benefits. Your long-term disability (LTD) benefits are designed to provide you with income if you are absent from work.
HSAs
Health Savings Accounts (HSAs) are often celebrated for their utility in managing health care expenses, particularly for those with high-deductible health plans in your city, your state. However, their benefits extend beyond medical cost management. In fact, HSAs can potentially act as superior retirement savings vehicles compared to traditional retirement plans like 401ks, especially after employer matching contributions are maxed out.
Understanding HSAs
HSAs are tax-advantaged accounts designed for individuals with high-deductible health insurance plans. For 2027, the IRS defines high-deductible plans as those with a minimum deductible of $1,750 for individuals or $3,500 for families. HSAs allow pre-tax contributions, tax-free growth of investments, and tax-free withdrawals for qualified medical expenses, making them a triple-tax-advantaged account.
The annual contribution limits for HSAs in 2027 are $4,500 for individuals and $9,000 for families, with an additional $1,000 allowed for those aged 55 and older. Unlike Flexible Spending Accounts (FSAs), HSA funds do not expire at the end of the year; they accumulate and can be carried over indefinitely.
Comparing HSAs to 401ks Post-Matching
Once an employer's maximum match in a 401k is reached, further contributions yield diminished immediate financial benefits. This is where HSAs can become a strategic complement. While 401ks offer tax-deferred growth and tax-deductible contributions, their withdrawals are taxable. HSAs, in contrast, provide tax-free withdrawals for medical expenses, which typically constitute a significant portion of retirement costs.
HSAs as a Retirement Tool
Post retirement, the HSA flexes its muscles as a robust tool. After age 65, funds can be withdrawn for any purpose, subject only to regular income tax if used for non-medical expenses (before 65, non-medical withdrawals also face a 20% additional tax). This flexibility is similar to that of traditional retirement accounts, but with the added advantage of tax-free withdrawals for medical costs, a significant benefit given the odds of facing rising health care expenses in retirement.
Furthermore, HSAs do not have required minimum distributions (RMDs), unlike 401ks and traditional IRAs, offering more control over tax planning in retirement. This makes HSAs particularly advantageous for those who might not need to tap into their savings immediately at retirement or who want to reduce their taxable income.
Investment Strategy for HSAs
Initially, it's prudent to invest conservatively within an HSA, focusing on maintaining sufficient liquid funds to cover near-term deductibles and other out-of-pocket medical expenses. However, once a financial cushion is established, treating the HSA like a retirement account by investing in a diversified mix of stocks and bonds can help enhance the account's growth potential over the long term.
Using HSAs in Retirement
In retirement, HSAs can cover a range of expenses:
The Bottom Line
HSAs offer unique advantages that can make them a superior option for retirement savings, particularly after you have contributed enough to receive the full 401k match. Their flexibility in fund usage, coupled with tax advantages, makes HSAs a key component of a comprehensive retirement strategy. By strategically managing contributions and withdrawals, individuals can pursue both their financial and physical health goals in retirement.


Make sure you submit this documentation to your employer's online pension center to avoid having your pension benefit delayed or suspended. They'll need this information regardless of how old the divorce or how short the marriage.
For more information on strategies to consider if divorce is affecting your retirement benefits, please give us a call.
In the process of divorcing?
If you retire from your employer before your divorce is final, you will need to elect a joint pension that provides your spouse with at least 50% of your benefits. To prevent this outcome, you'll need to get your spouse’s signed, notarized consent to a different election or a lump sum.
Alternatively, you can delay your retirement until after your divorce is final and provide your employer with the required divorce documentation in advance of claiming your pension.
In the unfortunate event that you pass away before collecting your benefits from your employer, your survivor will be responsible for taking action.
What your survivor needs to do:
If you have a joint pension:
If your survivor has medical coverage through your company: