In our comprehensive retirement guide for 3M employees in your city, your state, we go through many factors which you, at the age of retirement age, may take into account when deciding on the proper time to retire from 3M. Some of those factors include: healthcare & benefit changes, interest rates, current tax rates, inflation, and much more. Keep in mind we are not affiliated with 3M. We recommend reaching out to your 3M benefits department for further information.
Blogs You May Enjoy:

Source: Is it Worth the Money to Hire a Financial Advisor? The Balance, 2021
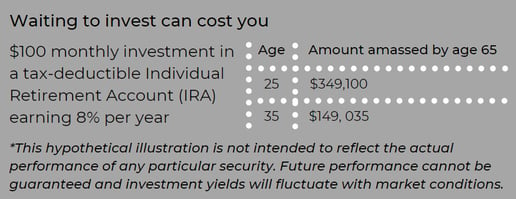
Starting to save as early as possible matters. Time on your side means compounding can have significant impacts on your future savings. And, once you’ve started, continuing to increase and make the most of your contributions for your 401(k) plan is key.

3M Employee Retirement Income Plan (ERIP) Overview
The 3M Employee Retirement Income Plan, which covers employees hired before January 1, 2009 and is set to freeze December 31, 2028, is a defined benefit plan made up of two groups with different formulas, Portfolio I and Portfolio II. The example below follows the Portfolio I formula, which uses a Social Security breakpoint; Portfolio II instead uses a Social Security integration level, and its lump sum equals the greater of the participant's total pension value when they leave 3M, grown 4% a year until the earlier of pension commencement or age 65, or the actuarial equivalent of the future annuity. In general, the pension benefit is based on a combination of factors, including:
* Pension Service (years of service): Employees accumulate benefits based on how many years they work at the company.
* Final Average Earnings: The pension is calculated based on the employee's High-4 average pension earnings: the greater of the highest four consecutive calendar years of pension earnings or the last 48 months of pension earnings before retirement.
* Accrual Rate: Each year of service contributes a percentage (known as the accrual rate) to the final pension amount. This rate ranges between 1-2% of the final average pay for each year of service.
* Normal Retirement Age (NRA): Normal Retirement Age is set at 65 years of age.
The formula used for existing participants will remain in effect until the freeze date on December 31, 2028.
However, for employees hired or rehired on or after January 1, 2009, 3M shifted its focus toward a 401(k)-based plan, no longer offering traditional pension benefits to those employees.
Eligibility:
Any employee of 3M or an affiliate who is a Participant in the ERIP, and who is within a designated class, shall be eligible to become a Member in this Nonqualified Plan III.
Key Features of the ERIP:
he 3M Employee Retirement Income Plan (ERIP) is a defined benefit pension plan designed to provide retirement income to eligible 3M employees.
The plan calculates benefits based on factors such as years of service, compensation, and age at retirement.
-
Employee Retirement Income Plan (ERIP) Formula Components
-
The defined benefit plan (ERIP) determines retirement benefits using a combination of an employee's age, length of service, average compensation during their career, and other factors explained below.
Please note that in the example shown below we are using the following assumptions:
1) Participant's age at Benefit Commencement Date (BCD): 59 and 3 months
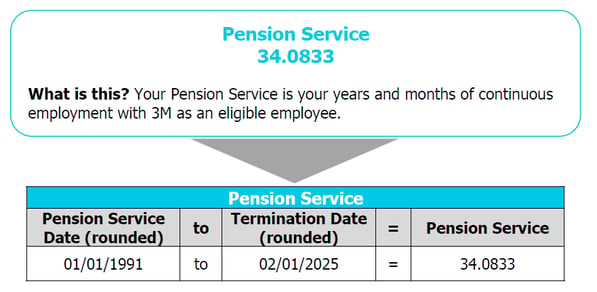
2) Pension Service Years: 34 years and 1 month
3) Earliest Unreduced Retirement Age: 62
4) Social Security Bridge Eligibility (Rule of 92; age + pension service years): Yes (59 + 34 = 93)
5) IRS Segment Rates Used (for Lump Sum calculation): 5.50%, 5.76%, 5.83
- * Pension Service (years of service): The total number of years an employee has worked for 3M.
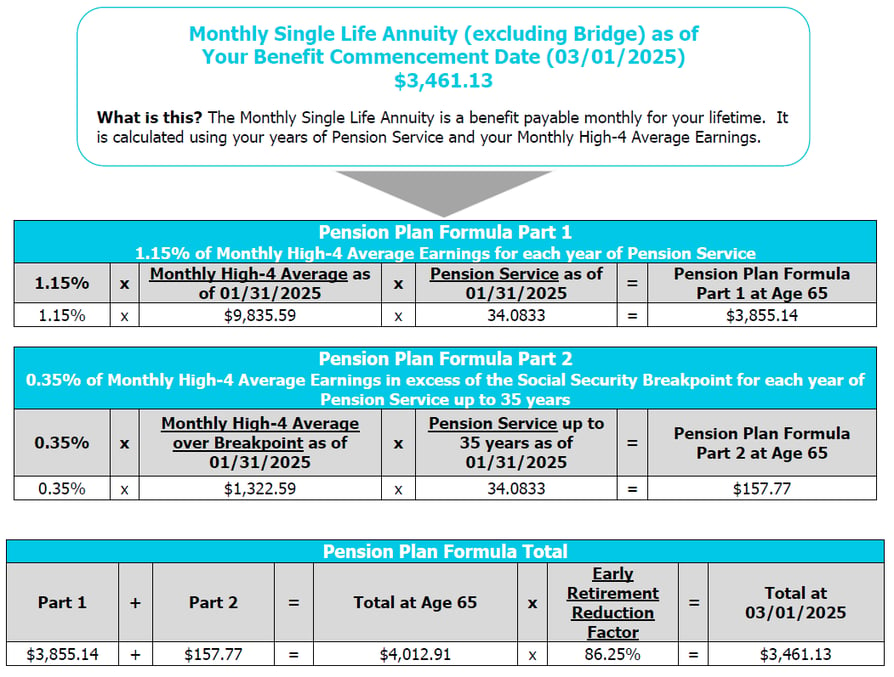
- * Monthly High-4 Average Pension Earnings: This refers to the average monthly salary over the highest consecutive four year period or your last 48 months of earnings converted to a monthly amount.
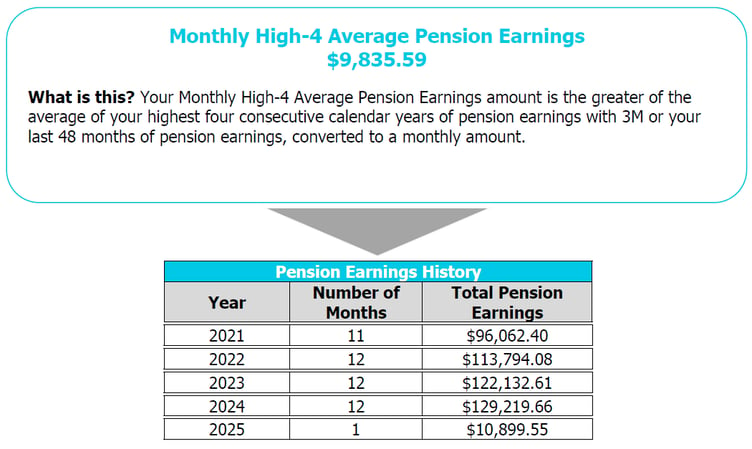
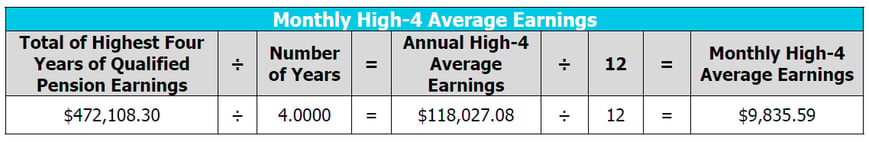
In the above example, the total Pension Earnings for the last 48 months equals $472,108. This amount divided by 48 months equals $9,835.59 which is the Monthly High-4 Average Pension Earnings.
* Monthly High-4 Average Pension Earnings Over Breakpoint: This refers to the amount that your Monthly High-4 Earnings (see previous calculation above) exceeds your Social Security Breakpoint (which is your 35-year Social Security wage base average).
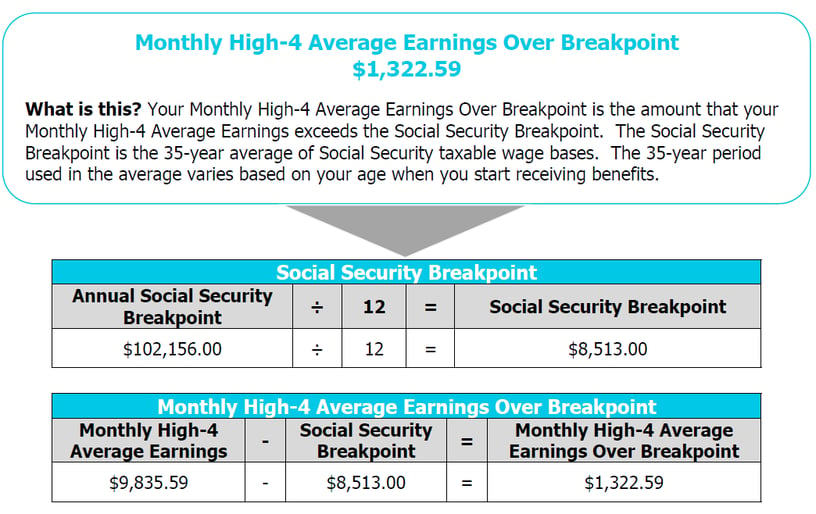
Using a 35-year average Social Security wage base of $102,156 divided by 12 months equals a Social Security Breakpoint amount of $8,513.
The difference between the Monthly High-4 Average Earnings ($9,835.59) and the Social Security Breakpoint ($8,513.00) is $1,322.59. This $1,322.59 amount is the Monthly High-4 Average Earnings Over Breakpoint amount.
* Early Retirement Reduction Factor: There is a reduction of 5% per year (or 1/12th of 5% per month) that your Benefit Commencement Date begins prior to your Earliest Unreduced Retirement Date.
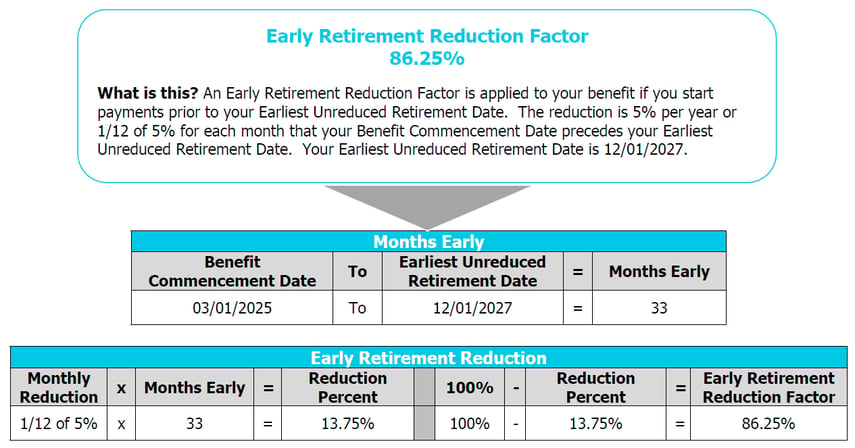
In the above example, based on a Benefit Commencement Date that begins 33 months prior to the Earliest Unreduced Retirement Date, the Reduction Percent equals 13.75%, and an Early Retirement Reduction Factor of 86.25%.
3M's pension plan allows early retirement beginning at age 55, as long as plan requirements are met.
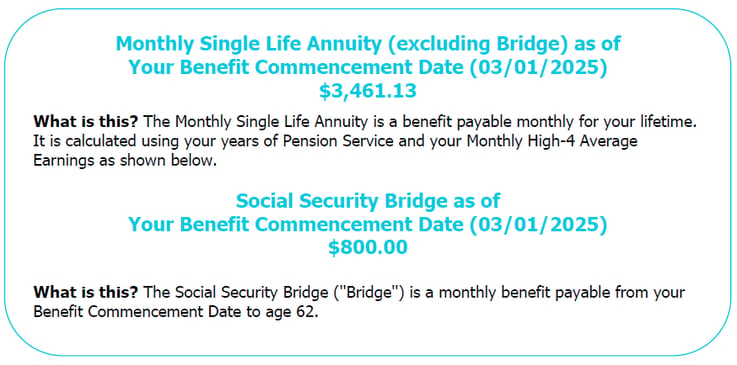
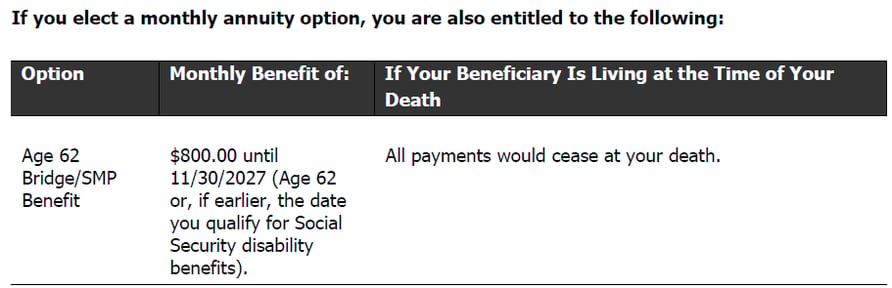
* Social Security Bridge: This represents a monthly benefit payable based on your Benefit Commencement Date to age 62. Eligibility is reached when age plus years of pension service is 92 or greater.
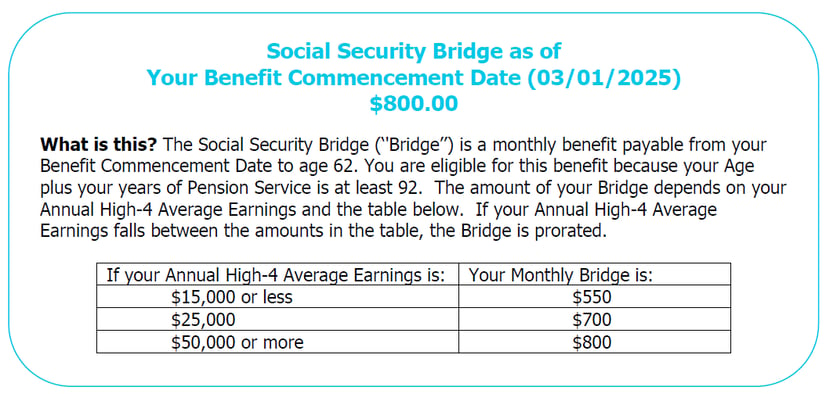
In our example above, the Annual High-4 Average Earnings is $50,000 or more so the monthly Social Security Bridge is $800 per month.
- * Benefit Multiplier: A percentage factor applied to the Pension Plan Part 1 Formula (Monthly High-4 Average Earnings), and the Pension Plan Part 2 Formula (Monthly High-4 Average Earnings in Excess of Social Security Breakpoint). The benefit multiplier used in our example are:
- Pension Plan Formula Part 1 = 1.15%
- Pension Plan Formula Part 2 = 0.35%
Example Single Life Annuity Calculation: The monthly Single Life Annuity is payable for the retiree's lifetime. Upon retiree's passing payments will cease, with no further benefits payable.
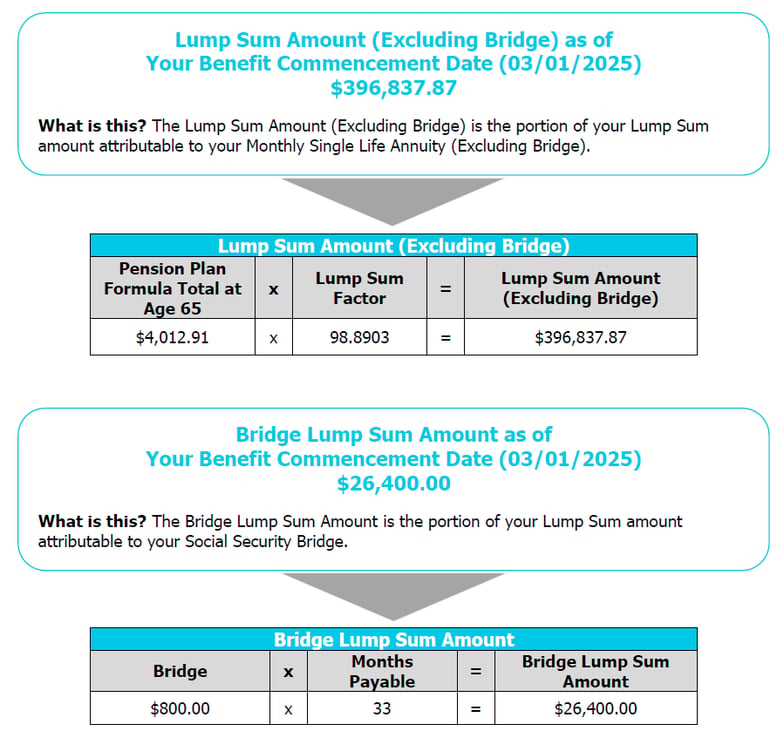
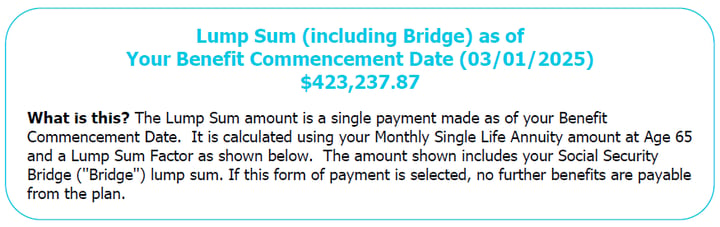
Example Lump Sum Calculation: The Lump Sum is derived from the monthly Single Life Annuity. It is the actuarially equivalent to the total annuity a retiree would have received as a Single Life Annuity recipient. No additional benefits will be paid after you receive a lump sum payment.
The Lump Sum is calculated using 417e Segment Rates from November of the calendar year preceding your Benefit Commencement Date. If you requested a Benefit Commencement Date beyond the current calendar year, your estimated Lump Sum was calculated using the last published November 417e Segment Rates. The 417e Segment Rates for November are typically published in mid-December. As a result, you should be aware that the amount of your Lump Sum payment could increase or decrease based on the actual 417e Segment Rates in effect on your Benefit Commencement Date.
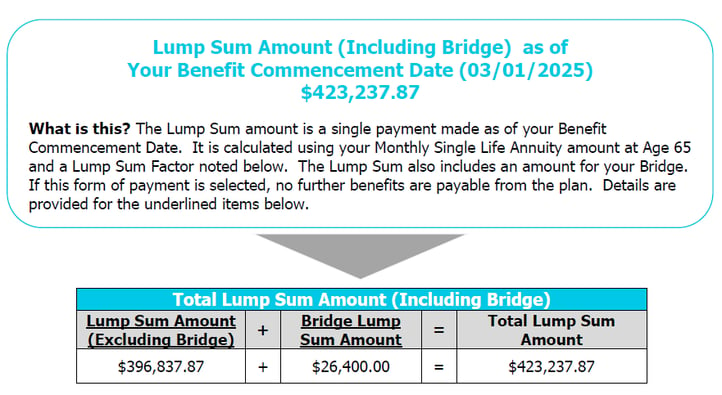
Total Lump Sum Including the Social Security Bridge (as previously discussed above).
Comparison: Single Life Annuity vs. Lump Sum
Single Life Annuity
Lump Sum
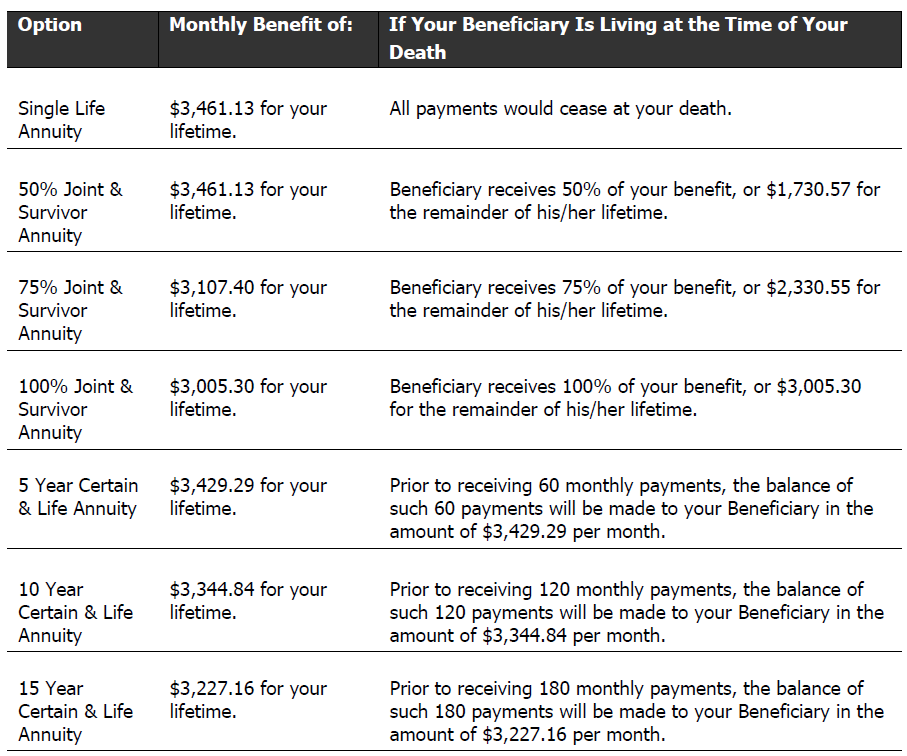
Comparison: Monthly Annuity Options
For precise information regarding your pension benefits, it's advisable to consult 3M's human resources or benefits department, as they can provide personalized details based on your employment history and the specific terms of the ERIP.
Note: The examples provided are for illustrative purposes only.
Considerations
Understanding the interest rate risks associated with pension plans is important. While annuities offer stability, they may lack inflation protection. Some retirees consider pairing their annuity election with additional retirement savings to help address rising costs.
For personalized advice regarding your 3M retirement plan, consult with a financial advisor familiar with 3M’s specific retirement offerings and policies. It’s important to review your Summary Plan Description (SPD) or similar documentation for detailed insights tailored to your career at 3M.
Conclusion
If you’re navigating your retirement options at 3M, reach out to The Retirement Group at(800) 900-5867 for expert guidance. They specialize in retirement planning for employees of major corporations like 3M and can provide clarity on your pension choices. Remember to always verify information against your company’s official documents, as The Retirement Group is independent from 3M and its affiliates.
3M 401k and Retirement Income Account (RIA)
The 3M Voluntary Investment Plan (VIP), 3M's 401(k) plan, offers employees an excellent opportunity to save for retirement with contributions from both the employee and the company. Here’s a detailed breakdown of how the plan works:
Eligibility:
- All active employees of 3M are eligible to participate in the plan from their date of hire.
- Employees can elect to contribute a percentage of their salary to their 401(k), and contributions are typically made on a pre-tax basis.
Employees who don't enroll on their own are automatically enrolled 45 days after hire (three months for Savings Plan participants) at a default before-tax contribution rate of 7% (6% for Savings Plan), invested in the 3M LifePath Portfolio target-date fund closest to the year they turn 65; the default rate then rises 1% a year up to a maximum of 10% unless the employee changes it.
Vesting:
- 3M provides immediate vesting for employee contributions. Company matching and Retirement Income Account contributions vest 40% after one year of service, 70% after two years and 100% after three years.
Employer Matching:
- 3M's match depends on when you were hired. VIP matching contributions range from 45% to 100% of the first 5% of eligible pay you contribute; employees hired or rehired on or after January 1, 2009 get the 100% rate on that first 5%, according to the 2016 Portfolio III VIP summary plan description, plus a separate 3% nonelective Retirement Income Account contribution on eligible pay. For example, if an employee hired after 2009 earns $100,000 per year and contributes 5% ($5,000), 3M would contribute a $5,000 match plus a $3,000 Retirement Income Account contribution, bringing the total contribution for the year to $13,000.
Example Calculation:
- If an employee hired on or after January 1, 2009 makes $80,000 annually and contributes 5% ($4,000) to their 401(k), 3M would match 100% of it. Therefore, 3M would contribute an additional $4,000 match plus a $2,400 Retirement Income Account contribution (3% of pay), making the total annual contribution $10,400.


Vesting:
The vesting schedule uses years of service to determine what percentage of your Company Match Account and Retirement Income Account is vested. You start to earn service beginning on your date of hire. It includes your active employment, time you are on approved absences from work such as vacations, Company holidays and short- or long-term disability as well as any period of military leave.
The chart below shows how the vesting schedule works:

Loans:
While actively employed, you may take out a loan from your 401(k) Accounts and/or Rollover Accounts. You can have up to two loans outstanding at any time. Only employees receiving regular wage payroll payments are eligible to take a loan. All loans are subject to an origination fee that is deducted from your loan amount. The minimum loan amount is currently $1,000 plus the loan origination fee.
The maximum loan amount is the lesser of:
- 50% of the total of your 401(k) Accounts, Rollover Accounts, Retirement Income Account, Company Contribution Account and vested Company Match Account, minus any outstanding loans; or
- $50,000 minus the highest outstanding loan balance you had during the last 12 months; or
- The sum of your 401(k) Account and Rollover Account balances invested in the Plan’s investment funds (excluding 3M stock and PCRA), minus $1,000 if you have a balance in the self-directed brokerage account (PCRA)
Withdrawals:

Distributions When You Leave 3M:

Over half of plan participants in your city your state, aged retirement age, admit they don’t have the time, interest, or knowledge needed to manage their 401(k) portfolio. But the benefits of getting help goes beyond convenience. Studies like this one, from Charles Schwab, show those plan participants who get help with their investments tend to have portfolios that perform better: The annual performance gap between those who get help and those who do not is 3.32% net of fees. This means a 45-year-old participant could see a 79% boost in wealth by age 65 simply by contacting an advisor. That’s a pretty big difference.
Getting help can be the key to better results across the 401(k) board.
A 2010 Charles Schwab study found several positive outcomes common to those using independent professional advice. They include:
- Improved savings rates – 70% of participants who used 401(k) advice increased their contributions.
- Increased diversification – Participants who managed their own portfolios invested in an average of just under four asset classes, while participants in advice-based portfolios invested in a minimum of eight asset classes.
- Increased likelihood of staying the course – Getting advice increased the chances of participants staying true to their investment objectives, making them less reactive during volatile market conditions and more likely to remain in their original 401(k) investments during a downturn. Don’t try to do it alone. Get help with your company's 401(k) plan investments. Your nest egg will thank you.
Net Unrealized Appreciation (NUA)
When you qualify for a distribution, you have three options:
- Roll-over your qualified plan to an IRA and continue deferring taxes.
- Take a distribution and pay ordinary income tax on the full amount.
- Take advantage of NUA and reap the benefits of a more favorable tax structure on gains.
How does Net Unrealized Appreciation work?
First an employee must be eligible for a distribution from their qualified company-sponsored plan. Generally, at retirement or age 59 1/2, the employee takes a 'lump-sum' distribution from the plan, distributing all assets from the plan within one tax (calendar) year. The portion of the plan that is made up of mutual funds and other investments can be rolled into an IRA for further tax deferral. The highly appreciated company stock is then transferred to a non-retirement account.
The tax benefit comes when you transfer the company stock from a tax-deferred account to a taxable account. At this time, you apply NUA and you incur an ordinary income tax liability on only the cost basis of your stock. The appreciated value of the stock above its basis is not taxed at the higher ordinary income tax but at long-term capital gains rates of 0%, 15%, or 20%, depending on your taxable income. Depending on your tax brackets, this could mean meaningful tax savings on the appreciation.
You may be interested in learning more about NUA with a complimentary one-on-one session with a financial advisor from The Retirement Group in your city, your state.
IRA Withdrawal
When you qualify for a distribution, you have three options:
Your retirement assets may consist of several retirement accounts: IRAs, 401(k)s, taxable accounts, and others.
So, what is the most efficient way to take your retirement income after leaving your company?
You may want to consider meeting your income needs in retirement by first drawing down taxable accounts rather than tax-deferred accounts.
This may help your retirement assets with your company last longer as they continue to potentially grow tax deferred.
You will also need to plan to take the required minimum distributions (RMDs) from any company-sponsored retirement plans and traditional or rollover IRA accounts.
IRS rules require you to begin taking distributions from these types of accounts when you reach your RMD age: 73 if you were born from 1951 through 1959, or 75 if you were born in 1960 or later. Beginning in 2023, the excise tax for every dollar of your RMD under-distributed was reduced from 50% to 25%, and it may be 10% if the shortfall is corrected in time.
Current rules allow account owners to delay taking their first RMD until April 1 following the later of the calendar year they reach RMD age or, in a workplace retirement plan, retire.
Two flexible distribution options for your IRA
When you need to draw on your IRA for income or take your RMDs, you have a few choices. Regardless of what you choose, IRA distributions are subject to income taxes and may be subject to penalties and other conditions if you’re under 59½.
Partial withdrawals: Withdraw any amount from your IRA at any time. If you’re retirement age or over, you’ll have to take at least enough from one or more IRAs to meet your annual RMD.
Systematic withdrawal plans: Structure regular, automatic withdrawals from your IRA by choosing the amount and frequency to meet your income needs after retiring from your company. If you’re under 59½, you may be subject to a 10% early withdrawal penalty (unless your withdrawal plan meets Code Section 72(t) rules).
Your tax advisor can help you understand distribution options, determine RMD requirements, calculate RMDs, and set up a systematic withdrawal plan.
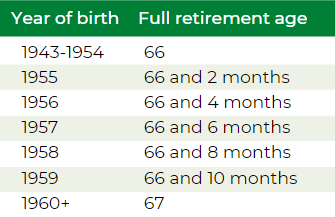
You and your Medicare-eligible dependents must enroll in Medicare Parts A and B when you first become eligible. Many company-sponsored retiree medical plans pay benefits as if Medicare Parts A and B paid first, whether or not you actually enroll, so check your company's plan for its rules.