2027 Tax Rates & Inflation
Each year the IRS adjusts tax brackets, deductions and retirement plan limits for inflation. These are the 2027 changes most likely to matter to employees who are approaching retirement:
The personal exemption remains at $0. The One, Big, Beautiful Bill Act made that change permanent.
Retirement account contributions: Pre-tax contributions to your employer's 401(k) plan may help reduce your taxable income. For 2027, employees can contribute up to $25,500 to 401(k), 403(b) and most 457 plans. Employees age 50 and over can add a catch-up contribution of up to $8,500, and employees age 60 through 63 may be able to make a higher catch-up of up to $11,750 if their plan allows it. If your 2026 Social Security wages from the employer sponsoring your plan were above $155,000, any 2027 catch-up contributions must be made as Roth (after-tax) contributions. The IRA contribution limit for 2027 is $7,500, plus a catch-up amount for those age 50 and over.
Charitable deduction for non-itemizers: Beginning with tax year 2026, taxpayers who take the standard deduction may deduct up to $1,000 ($2,000 joint) of cash gifts to eligible charities. Gifts to donor-advised funds and non-cash gifts do not qualify.
Child Tax Credit: For 2027, the Child Tax Credit is up to $2,300 per qualifying child. The credit begins to phase out above $200,000 ($400,000 joint) of modified adjusted gross income.
Remote work and state taxes: If you work remotely in a different state from your employer's office, you may owe tax in more than one state. Some states, including New York, apply a "convenience of the employer" rule that can tax a remote employee's wages as if the work were done in that state. A tax advisor can help you review whether credits or other options apply to your situation.
2027 Federal Income Tax Brackets
| Rate | Single | Married Filing Jointly | Married Filing Separately | Head of Household |
|---|---|---|---|---|
| 10% | $0 - $12,800 | $0 - $25,600 | $0 - $12,800 | $0 - $18,250 |
| 12% | $12,801 - $52,025 | $25,601 - $104,050 | $12,801 - $52,025 | $18,251 - $69,650 |
| 22% | $52,026 - $109,125 | $104,051 - $218,250 | $52,026 - $109,125 | $69,651 - $109,100 |
| 24% | $109,126 - $208,325 | $218,251 - $416,650 | $109,126 - $208,325 | $109,101 - $208,300 |
| 32% | $208,326 - $264,550 | $416,651 - $529,100 | $208,326 - $264,550 | $208,301 - $264,550 |
| 35% | $264,551 - $661,375 | $529,101 - $793,650 | $264,551 - $396,825 | $264,551 - $661,350 |
| 37% | $661,376+ | $793,651+ | $396,826+ | $661,351+ |
Source: IRS Rev. Proc. 2026-35, section 3.01, Tables 1-4 (IR-2026-133, November 5, 2026).
Inflation reduces purchasing power over time, so the same goods and services cost more as prices rise. Social Security benefits rise 3.6% in January 2027 through the annual cost-of-living adjustment. When building a retirement income plan, consider inflation assumptions, Medicare premiums, prescription drug costs and other health care expenses alongside the 2027 tax brackets and deductions above. For 2027, the standard Medicare Part B premium is $209.40 a month and the annual deductible is $292. The Part A inpatient hospital deductible is $1,776 per benefit period. Hospital coinsurance is $444 a day for days 61 through 90 and $888 a day for lifetime reserve days. Skilled nursing facility coinsurance is $222 a day for days 21 through 100. Out-of-pocket spending on covered Part D drugs is capped at $2,400.
Sources: IRS, Social Security Administration, Centers for Medicare & Medicaid Services.
No matter where you stand in the planning process, or your current age, we hope this guide provides you a good overview of the steps to take and resources that help you simplify your transition from your company into retirement and get the most from your benefits.
You know you need to be saving and investing, especially since time is on your side the sooner you start, but you don’t have the time or expertise to know if you’re building retirement savings that can last after leaving your company.
Source: Is it Worth the Money to Hire a Financial Advisor? The Balance
Starting to save as early as possible matters. Time on your side means compounding can have significant impacts on your future savings. And, once you’ve started, continuing to increase and make the most of your contributions for your 401(k) plan is key.
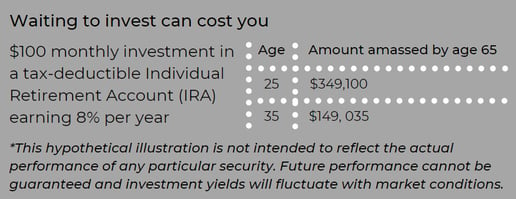
*Source: Bridging the Gap Between 401(k) Sponsors and Participants, T.Rowe Price.
As decades go by, you’re likely full swing into your career at your company and your income probably reflects that. However, the challenges of saving for retirement start coming from large competing expenses: a mortgage, raising children, and saving for their college.
One of the classic planning conflicts is saving for retirement versus saving for college. Most financial planners will tell you that retirement from your company should be your top priority because your child can usually find support from financial aid while you’ll be on your own to fund your retirement.
How much we recommend that you invest towards your retirement is always based on your unique financial situation and goals. However, consider investing a minimum of 10% of your salary toward retirement through your 30s and 40s.
As you enter your 50s and 60s, you’re ideally at your peak earning years with some of your major expenses, such as a mortgage or child-rearing, behind you or soon to be in the rearview mirror. This can be a good time to consider whether you have the ability to boost your retirement savings goal to 20% or more of your income. For many people, this could potentially be the last opportunity to stash away funds.
In 2027, workers can contribute up to $25,500 into their retirement plan/401(k), and workers age 50 or older can add an additional $8,500 in catch-up contributions for a combined annual total of $34,000.
These retirement savings vehicles give you the chance to take advantage of three main benefits:
According to Costco's 2022 proxy statement, the company does not maintain a pension plan or a post-retirement medical plan for any employee. For Costco employees, the 401(k) Retirement Plan covered in Section 4 is the primary company-sponsored retirement savings plan, so there is no pension lump-sum-versus-annuity election to make.
Costco's Deferred Compensation Plan is designed to help employees defer a portion of their compensation until a future date, typically retirement. This allows participants to reduce their taxable income during their working years and defer taxes on the deferred amounts until they receive the payouts.
The Deferred Compensation Plan is generally available to certain management and highly compensated employees, though the specific eligibility criteria can vary.
Employees become eligible after a certain tenure or once they reach a specific compensation threshold. The exact eligibility and entry terms for Costco employees may be found in the details of the plan document.
Let’s assume an eligible employee chooses to defer $20,000 of their annual salary under Costco’s Deferred Compensation Plan.
If the employee is in the 35% tax bracket, deferring the $20,000 would reduce their taxable income, potentially saving them $7,000 in taxes in the current year (35% of $20,000).
If this amount is deferred and invested in a portfolio that earns an annual return of 5%, after 10 years, the employee would have:
Future Value = 20,000 × (1+0.05)10 = 20,000 × 1.62889 = 32,577.80
Thus, the deferred amount would grow to $32,577.80, which would be taxed when withdrawn during retirement at a potentially lower tax rate.
This is a simplified example, and actual results would depend on investment choices and market performance.
Please refer to the plan's full provisions for the most accurate and detailed information.
Stock Incentive Plan
Costco’s 2019 Incentive Plan provides eligible employees with equity-based compensation in the form of restricted stock units (RSUs).
The plan is designed to align the interests of employees with those of shareholders, fostering a focus on long-term company success.
Restricted Stock Units (RSUs):
RSUs are granted to employees and represent a promise to deliver Costco shares at a future date.
They are a form of long-term equity compensation awarded to eligible employees and non-employee directors.
These units vest over time or upon the achievement of performance metrics. Once the RSUs vest, they convert to shares, which the employee can sell or hold.
Retirees who are eligible for a pension are often offered the choice of receiving their pension payments for life, or receive a lump-sum amount all-at-once. The lump sum is the equivalent present value of the monthly pension income stream – with the idea that you could then take the money (rolling it over to an IRA), invest it, and generate your own cash flow by taking systematic withdrawals throughout your retirement years.
The upside of electing the monthly pension is that the payments are designed to continue for life (at least to the extent that the pension plan itself remains in place and solvent and doesn’t default). Thus, whether you live 10, 20, 30, or more years after retiring from your company, the monthly pension is designed to keep paying, which may help address the risk of outliving your income.
The major downside of the monthly pension are the early and untimely passing of the retiree and joint annuitant. This often translates into a reduction in the benefit or the pension ending altogether upon the passing. The other downside, it that, unlike Social Security, company pensions rarely contain a COLA (Cost of Living Allowance). As a result, with the dollar amount of monthly pension remaining the same throughout retirement, it will lose purchasing power when the rate of inflation increases.
In contrast, selecting the lump-sum gives you the potential to invest, earn more growth, and potentially generate even greater retirement cash flow. Additionally, if something happens to you, any unused account balance will be available to a surviving spouse or heirs. However, if you fail to invest the funds for sufficient growth, there’s a danger that the money could run out altogether and you may regret not having held onto the pension’s “income for life” feature.
Ultimately, the “risk” assessment that should be done to determine whether or not you should take the lump sum or the lifetime payments that your company pension offers, depends on what kind of return must be generated on that lump-sum to replicate the payments of the annuity. After all, if it would only take a return of 1% to 2% on that lump-sum to create the same monthly pension cash flow stream, there is less risk that you will outlive the lump-sum. However, if the pension payments can only be replaced with a higher and much riskier rate of return, there is, in turn, a greater risk those returns won’t manifest and you could run out of money.
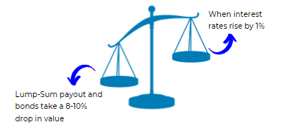
Current interest rates, as well as your life expectancy at retirement, have a significant impact on lump sum payouts of defined benefit pension plans.
Rising interest rates have an inverse relationship to pension lump sum values. The reverse is also true; decreasing or lower interest rates will increase pension lump sum values. Interest rates are important for determining your lump sum option within the pension plan.
The Retirement Group believes all employees should obtain a detailed RetireKit Cash Flow Analysis comparing their lump sum value versus the monthly annuity distribution options, before making their pension elections.
As enticing as a lump sum may be, the monthly annuity for all or a portion of the pension, may still be an attractive option, especially in a high interest rate environment.
Each person’s situation is different, and a complimentary Cash Flow Analysis, from The Retirement Group, will show you how your pension choices stack up and play out over the course of your retirement years which may be two, three, four or more decades in retirement.
By knowing where you stand, you can make a more prudent decision regarding the optimal time to retire, and which pension distribution option meets your needs the best.
401(k) Savings Plan
Employees are encouraged to enroll in a 401(k) savings plan right away. You may invest on a before-tax and/or an after-tax basis (regular or Roth) and choose various investment options, with varying degrees of risk.
In 2027, workers can contribute up to $25,500 into their 401(k), and for those 50 and older, they can add an additional $8,500 in catch-up contributions for a combined annual total of $34,000. Workers age 60 to 63 may be able to make a higher catch-up of $11,750 if their plan allows. These limits are adjusted annually for inflation.
You can also roll over pre-tax and Roth amounts from other eligible plans.
Vesting
For participants employed on or after August 1, 2024, Costco's 401(k) employer contributions are 100% vested and nonforfeitable, so there is no vesting-service requirement for them.
In addition, if you have an account in an eligible plan of a former employer, you may be eligible to roll over a distribution from that account to the Savings Plan.
When you retire, if you have balances in your 401(k) plan, you will receive a Participant Distribution Notice in the mail. This notice will show the current value that you are eligible to receive from each plan and explain your distribution options. It will also tell you what you need to do to receive your final distribution. Please call The Retirement Group at (800)-900-5867 for more information and we can get you in front of a retirement-focused advisor.
Costco's 401(k) Retirement Savings Plan offers several features to help employees build their retirement savings effectively
Contributions:New participants are automatically enrolled at a 4% salary deferral rate, which automatically increases by one percentage point on each employment anniversary up to a maximum of 20%; employees may opt out of automatic enrollment and the automatic increases.
Employer Matching : For most employees (those not covered by the Teamsters agreements), Costco matches the lesser of 50% of an employee's deferral contribution or $500 per year. Employees covered by the Teamsters agreements are instead eligible, after one year of service, for an annual employer contribution of $0.05 to $0.47 per straight-time hour worked (up to 2,080 hours a year), based on years of service.
The 401(k) plan has a 50% limit on investment in Costco stock.
Let’s assume an employee named John earns $50,000 annually and decides to contribute 5% of his salary to the 401(k) plan, which is $2,500 per year.
For most employees (those not covered by the Teamsters agreements), Costco matches 50% of contributions up to $500 a year, so it would contribute an additional $500 annually to John’s 401(k) account. After one year of service, these employees may also receive an annual discretionary employer contribution of 4% to 9% of pay based on years of service, which this example leaves out.
Assuming an average annual return of 7% from the investments within the 401(k) plan, here’s how John’s account might grow over 10 years:
* After 10 years, with an annual return rate of 7%, John's total amount in the 401(k) plan would grow to approximately $5,901.45 (without additional contributions beyond the initial amount).
* After 10 years, with an annual return rate of 7%, John's total amount in the 401(k) plan would grow to approximately $41,449 (with $3,000/year contributions during the ten year period).
This example illustrates how regular contributions to a 401(k) plan, coupled with employer matching and the power of compound interest, can significantly increase an employee's retirement savings over time.
Over half of plan participants admit they don’t have the time, interest or knowledge needed to manage their 401(k) portfolio. But the benefits of getting help goes beyond convenience. Getting help may make it easier to build a diversified portfolio and stick with it through market swings. 
Getting help can be the key to better results across the 401(k) board.
A 2010 Charles Schwab study found several positive outcomes common to those using independent professional advice. They include:
Rolling Over Your 401(k)
Borrowing from your 401(k)
Should you? Maybe you lose your job with your company, have a serious health emergency, or face some other reason that you need a lot of cash. Banks make you jump through too many hoops for a personal loan, credit cards charge too much interest, and … suddenly, you start looking at your 401(k) account and doing some quick calculations about pushing your retirement from your company off a few years to make up for taking some money out.
We understand how you feel: It’s your money, and you need it now. But, take a second to see how this could adversely affect your retirement plans after leaving your company.
Consider these facts when deciding if you should borrow from your 401(k). You could:
When you qualify for a distribution, you have three options:
How does Net Unrealized Appreciation work?
First an employee must be eligible for a distribution from their qualified company-sponsored plan. Generally, at retirement or age 59 1⁄2, the employee takes a 'lump-sum' distribution from the plan, distributing all assets from the plan within one tax (calendar) year. The portion of the plan that is made up of mutual funds and other investments can be rolled into an IRA for further tax deferral. The highly appreciated company stock is then transferred to a non-retirement account.
The tax benefit comes when you transfer the company stock from a tax-deferred account to a taxable account. At this time, you apply NUA and you incur an ordinary income tax liability on only the cost basis of your stock. The appreciated value of the stock above its basis is not taxed at the higher ordinary income tax but at long-term capital gains rates of 0%, 15%, or 20%, depending on your taxable income. Depending on your tax brackets, this could mean meaningful tax savings on the appreciation.
You may be interested in learning more about NUA with a complimentary one-on-one session with a financial advisor from The Retirement Group.
When you qualify for a distribution, you have three options:
Your retirement assets may consist of several retirement accounts: IRAs, 401(k)s, taxable accounts, and others.
So, what is the most efficient way to take your retirement income after leaving your company?
You may want to consider meeting your income needs in retirement by first drawing down taxable accounts rather than tax-deferred accounts.
This may help your retirement assets with your company last longer as they continue to potentially grow tax deferred.
You will also need to plan to take the required minimum distributions (RMDs) from any company-sponsored retirement plans and traditional or rollover IRA accounts.
Under current IRS rules, many account owners must begin taking required minimum distributions from these types of accounts at age 73 (age 75 for those born in 1960 or later). SECURE 2.0 reduced the excise tax for each under-distributed RMD dollar from 50% to 25%, with a further reduction possible when corrected timely.
Your first RMD can be delayed until April 1 of the year after you reach RMD age, and if you are still working (and do not own 5% or more of the company), RMDs from your current employer's plan can generally wait until April 1 of the year after you retire. This still-working exception does not apply to IRAs.
Two flexible distribution options for your IRA
When you need to draw on your IRA for income or take your RMDs, you have a few choices. Regardless of what you choose, IRA distributions are subject to income taxes and may be subject to penalties and other conditions if you’re under 59½.
Partial withdrawals: Withdraw any amount from your IRA at any time. If you’re 73 or over, you’ll have to take at least enough from one or more IRAs to meet your annual RMD.
Systematic withdrawal plans: Structure regular, automatic withdrawals from your IRA by choosing the amount and frequency to meet your income needs after retiring from your company. If you’re under 59½, you may be subject to a 10% early withdrawal penalty (unless your withdrawal plan meets Code Section 72(t) rules).
Your tax advisor can help you understand distribution options, determine RMD requirements, calculate RMDs, and set up a systematic withdrawal plan.
Costco offers a comprehensive benefits package that encompasses competitive wages, healthcare coverage, retirement savings plans, employee stock purchase plans, and various other perks and support programs.
Here’s an in-depth look at how these benefits work, who is eligible, and when eligibility starts:
Healthcare Coverage:
Part-time employees who have worked for at least 180 consecutive days and average more than 23 hours per week are eligible for Costco's health benefits plan. This includes medical, dental, and vision coverage.
Full-time employees receive more substantial contributions toward their healthcare premiums compared to part-time workers.
Retirement Savings Plans (401(k)):
Costco offers a 401(k) plan where employees can contribute a portion of their income pre-tax towards retirement savings.
The company provides generous matching contributions, enhancing the employees’ savings for retirement.
Employee Stock Purchase Plan (ESPP):
Employees can purchase Costco stock at a discounted price, which fosters a sense of ownership and participation in the company's success.
Paid Time Off (PTO):
Employees start accruing paid time off after 90 days of employment.
The accrual rate increases with the length of service, rewarding long-term employees.
Educational Assistance:
Costco supports its employees' educational aspirations through tuition reimbursement for higher education or professional development courses.
Direct Stock Purchase and Dividend Reinvestment Plan
Costco’s Direct Stock Purchase and Dividend Reinvestment Plan allows employees to directly purchase Costco stock and reinvest dividends.
This plan is administered by Computershare, and it is designed for long-term investors who want to build their Costco stock ownership over time.
Direct Stock Purchase:
Investors can purchase Costco shares without needing a brokerage account.
The minimum initial investment for non-shareholders is $250, but alternatively, participants can authorize monthly automatic deductions of at least $25 to fund the investment.
Investors can also make subsequent purchases with a minimum of $25 per transaction.
The plan allows for purchasing fractional shares based on the dollar amount of the investment.
Dividend Reinvestment:
Shareholders can choose to reinvest dividends into additional shares of Costco stock automatically. This reinvestment can be full or partial, depending on the number of shares owned.
A $15 purchase fee is deducted from the initial purchase; other purchase and dividend reinvestment fees follow Computershare's current fee schedule for the plan.
Costco’s Health Care Reimbursement Account (HCRA) allows eligible employees to set aside pre-tax dollars to pay for qualified medical expenses, thereby reducing their taxable income.
Let’s assume an employee elects to contribute $1,500 to their HCRA for the year.
Funds from the HSA can be used to pay for or reimburse qualified medical expenses such as doctor’s visits, prescription medications, and other health-related expenses not covered by insurance.
Contributions are made pre-tax, and reimbursements for qualified medical expenses are tax-free. Unlike an HSA, the account is not invested, and unused funds above any carryover the plan allows are forfeited at year end.


Divorce doesn’t disqualify you from survivor benefits. You can claim a divorced spouse’s survivor benefit if the following are true:
In the process of divorcing?
If your divorce isn’t final before your retirement date from your company, you’re still considered married. You have two options:
Source: The Retirement Group, “Retirement Plans - Benefits and Savings,” U.S. Department of Labor; “Generating Income That Will Last Throughout Retirement,” Fidelity
In the unfortunate event that you aren’t able to collect your benefits from your company, your survivor will be responsible for taking action.
What your survivor needs to do:
If you have a joint pension:
If your survivor has medical coverage through your company:
https://www.nerdwallet.com/article/taxes/federal-income-tax-brackets