2027 Tax Changes & Inflation

Blogs You May Enjoy:

Source: Is it Worth the Money to Hire a Financial Advisor? The Balance
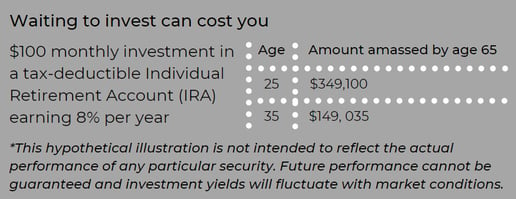
Starting to save as early as possible matters. Time on your side means compounding can have significant impacts on your future savings. And, once you’ve started, continuing to increase and make the most of your contributions for your 401(k) plan is key.

Pension Plan for Large Healthcare Companies in Minneapolis
The Pension Plan is a defined benefit pension plan provided by healthcare companies to support its employees in retirement. This plan is designed to provide eligible employees a consistent income during their retirement years, calculated based on their years of service and compensation history. Here is a detailed overview of the plan, simplified for better understanding.
Plan Overview
Healthcare companies pension plan has been established since 1925 and offers various formulas to calculate retirement benefits:
- Final Average Pay (FAP) Benefit Formula
- Annual Accumulation (AA) Benefit Formula
- Stable Lump Sum (SLS) Benefit Formula
Eligibility and Participation
Who is eligible?
- Employees aged 21 or older.
- Regular employees of healthcare companies age 21 or older (excluding temporary, on-call, supplemental or casual employees, and residents, research fellows and students).
How Your Benefit is Determined
Your pension benefits depend on when you became eligible and the specific formula applied during your service period. For all three formulas, Benefit Service is capped at a lifetime of 30 years.
Minimum Benefit: Your benefit will never be less than $30 times your years of Benefit Service with no maximum on the number of years of Benefit Service for service prior to January 1, 2015.
Let's break down the three pension plans:
1. Final Average Pay (FAP) Benefit Formula (Prior to January 1, 2015)
This formula is based on your average monthly compensation over the highest 36 consecutive months within the last 120 months of service before January 1, 2015, and the Annual Accumulation formula for your service beginning January 1, 2015.
The following Benefit Formula is used to calculate your benefit through December 31, 2014: Final Average Pay times Pension Percentage less Covered Compensation Offset equals Monthly pension benefit payable at Normal Retirement Date.
FAP Benefit Formula (prior to January 1, 2015)
(Final Average Pay X Pension Percentage*) - Covered Compensation Offset**
=
Monthly Pension Benefit Payable (at NRA)
*Pension Percentage: 2% per year of benefit service (up to 30 years).
**Covered Compensation Offset: changes each Plan Year. A monthly dollar amount equal to one twelfth of Covered Compensation (see table below) which is the average, without indexing, of the taxable wage base under the Social Security in effect for each calendar year during the last 35 – year period which the participant attains Social Security retirement age or, if less, the ((Final Average Pay x (.6% x years of Benefit Service)) up to a maximum of 30 years.
The following table provides the monthly dollar amounts equal to one-twelfth of Covered Compensation.


Example Financial Average Pay Calculation:
Participant reaches age 65 in 2023 with 32 years of Benefit Service earned as of December 31, 2014. The year of birth to use from the Covered Compensation table is 1958.

VS.

Because the result of the Benefit Formula calculation is greater than the result using the minimum benefit calculation, the monthly Final Average Pay benefit payable at age 65 in a life only annuity would be $1,680.
2. Annual Accumulation Benefit Formula (From January 1, 2015)
The Annual Accumulation benefit is calculated as a monthly payment for life starting at the participant’s Normal Retirement Date (usually age 65). Participant will continue to accrue a benefit in the Annual Accumulation formula after January 1, 2023 unless there is a break in service or if the participant elects the Stable Lump Sum formula beginning on January 1, 2024.
The formula calculates benefits annually which accumulates with each year of service beginning January 1, 2015.
You will continue to accrue a benefit in the Annual Accumulation formula after January 1, 2023, unless you have a break in service or elected the Stable Lump Sum formula during the healthcare companies Retirement Choice program beginning on January 1, 2024.
(Monthly Compensation* X Pension Percentage**) - Covered Compensation Offset***
=
Monthly Pension Benefit Payable (at NRA)
*Monthly Compensation: Recognized Compensation paid to you during the plan year multiplied by one-twelfth (1/12th). If you normally work less than the full regular schedule (80 hours per pay period), your basic monthly salary rate is expanded to an equivalent full-time rate. Generally, if you receive service credit during an approved leave of absence, you will also be deemed to have Recognized Compensation during that leave at your salary rate in effect before the leave.
**Pension Percentage Two percentage points (2%) multiplied by one year (or decimal fraction of a year) of Benefit Service for the Plan Year.
***Covered Compensation Offset; a monthly dollar amount equal to one twelfth of the Social Security Wage Base for the Plan Year or, if less, your Monthly Compensation times .6% times your years of Benefit Service up to a maximum of 30 years.
Example Annual Accumulation Benefit Calculation:
For Plan Year 2023, the Participant has an Annual Salary of $60,000 and has earned 1 year of Benefit Service. The Social Security Wage Base (SSWB) for 2023 is $13,350 ($160,200 divided by 12).

The Annual Accumulation benefit calculation will be repeated each year until the participant has accrued 30 years of benefit service or terminates employment.
3. Stable Lump Sum Benefit Formula (From January 1, 2023)
The Stable Lump Sum is calculated as a lump sum payment on your Normal Retirement Date (usually age 65).
Note on rehiring after a break in service: If you have a break in service and return to covered employment, you will enter the Stable Lump sum formula in effect as of your date of rehire. Any prior benefit earned in a prior formula will be preserved and added to your most recent accrual.
Employees who were active participants in the plan as of December 31, 2022 will continue to accrue a benefit in the Annual Accumulation formula unless the Stable Lump Sum Formula was elected during the healthcare companies Retirement Choice program. The healthcare companies Retirement Choice program was offered between August 14, 2023 and September 15, 2023. Those who elected to move into the Stable Lump Formula during that time will begin accruing in the Stable Lump Sum Formula beginning on January 1, 2024. Any benefit accrued prior to January 1, 2024 will be calculated under the applicable prior formulas.
The Stable Lump Sum formula is expressed as a one-time lump sum payment payable at age 65. The benefit is calculated annually using a percentage of annual compensation multiplied by benefit service. Each year, the lump sum value is determined and added to prior years’ accruals which results in the total Stable Lump Sum benefit. Even though the formula calculates as a lump sum value, the benefit is still converted to a monthly annuity and a monthly annuity is the automatic form of payment if no election is made.
Stable Lump Sum Benefit Formula (beginning January 1, 2023)
(Base Benefit)* + (Supplemental Benefit)**
=
Lump Sum (at NRA)
Base Benefit:
(Annual Compensation***) x (18%) x (max 1 Benefit Service Year)
Annual Compensation (up to 401(a) limit): Recognized Compensation paid to you during the plan year. If you normally work less than the full regular schedule (80 hours per pay period), your basic monthly salary rate is expanded to an equivalent full-time rate. Generally, if you receive service credit during an approved leave of absence, you will also be deemed to have Recognized Compensation during that leave at your salary rate in effect before the leave. Annual Compensation is limited by federal law.
Supplement Benefit:
((Annual Compensation > SSWB**** up to 401(a) Limit)) x (8%) x (max 1 Benefit Service Year)
Annual Compensation over SSWB: the Recognized Compensation paid to you during the plan year that is over the Social Security Wage Base in effect for that year.
Example Stable Lump Sum Benefit Calculation:
For Plan Year 2023, the Participant has an Annual Salary of $60,000 and has earned 1 year of Benefit Service. The Social Security Wage Base (SSWB) for 2023 is $160,200.

Because the compensation is under the SSWB, there is no additional benefit using 8%. The Stable Lump Sum Accrual for plan year 2023 is $10,800 payable as a one-time lump sum at Normal Retirement Date.
This calculation will be repeated each year until the participant has accrued 30 years of total benefit service or terminates employment.
Can I Take the Healthcare Companies Final Average Pay Pension Plan as a Lump Sum?
Yes, you can take the healthcare companies Final Average Pay Pension Plan as a lump sum. The lump sum is calculated by converting your annuity to its present value using the interest rates prescribed by the IRS.
Interest Rate for Present Value Calculation
The interest rate used to determine the present value of the Final Average Pay annuity is based on the IRS-prescribed interest rates. These rates are updated periodically and are crucial in calculating the lump sum value of your pension.
Age Penalties on the Pension Plans
Penalties apply if you choose to start receiving your pension benefits before the normal retirement age (usually 65). The reduction is based on actuarial adjustments to account for the longer payment period.
- Final Average Pay and Annual Accumulation Formulas:
- Early retirement percentages apply, with reductions based on your age and years of continuous service.
- The reduction is calculated using specific tables (Table A and Table B) provided in the plan.
- Stable Lump Sum Formula:
- Reductions are based on the 417(e) interest rates and mortality rates in effect for the plan year.
Five Common Questions
-
What happens if I leave my healthcare company before I am vested?
You may lose all accrued benefits if you terminate employment before becoming vested.
-
How are cost-of-living increases applied?
If eligible, your benefits may be adjusted annually based on the Consumer Price Index, capped at 1.5%.
-
What benefits are available if I become disabled?
If disabled, you continue to accrue benefits based on your salary rate at the time of disability.
-
What death benefits are provided?
If you die before starting your pension, a death benefit is provided to your beneficiary, usually in the form of an annuity or lump sum.
-
How do I file a claim for my pension benefits?
Claims must be filed in writing to the Retirement Plan Claims Committee. Detailed procedures for filing and appealing claims are outlined in the plan.
Questions and Answers on Healthcare Companies Pension Plans
-
What is the Final Average Pay plan?
The Final Average Pay plan calculates your pension based on the average of your highest 36 consecutive months of pay. The benefit is determined by multiplying this average pay by a pension percentage, which is 2% times your years of benefit service, and then subtracting a covered compensation offset based on Social Security Wage Base (SSWB) limits.
-
How is the Annual Accumulation plan structured?
The Annual Accumulation plan calculates benefits annually based on your monthly compensation. Each year, a portion of your compensation is multiplied by a pension percentage (2% per year of service) and then reduced by a covered compensation offset. The accrued benefits are added up annually and paid out as a monthly annuity at retirement.
-
What is the Stable Lump Sum plan?
The Stable Lump Sum plan allows participants to accrue benefits annually as a lump sum. Each year's benefit is calculated by multiplying your annual compensation by a base percentage (18% for compensation up to the 401(a) limit and 8% for compensation over the SSWB). These annual lump sums accumulate until retirement, when they can be paid out as a single lump sum or converted to a monthly annuity.
-
Can I take the Final Average Pay plan as a lump sum?
Yes, you can take the Final Average Pay plan as a lump sum. The lump sum is calculated by converting the annuity payments you would receive at retirement into a present value using interest rates and mortality tables prescribed by the IRS.
-
How is the interest rate determined for calculating the present value of the Final Average Pay annuity?
The interest rate used to calculate the present value of the Final Average Pay annuity is based on IRS-prescribed rates, which are updated periodically. These rates reflect the current market conditions and are applied to determine the lump sum equivalent of the annuity payments.
-
Are there age penalties for early retirement under the Final Average Pay plan?
Yes, if you retire before the normal retirement age of 65, your benefits under the Final Average Pay plan may be reduced. The reduction depends on how many years early you retire and the specific reduction factors applicable at the time of your retirement.
-
What age penalties apply to the Annual Accumulation plan?
Similar to the Final Average Pay plan, retiring early under the Annual Accumulation plan can result in reduced benefits. The reduction is based on the number of years you retire before age 65 and the actuarial adjustment factors in place.
-
Are there age penalties under the Stable Lump Sum plan?
The Stable Lump Sum plan calculates benefits to be payable at age 65. If you choose to take your lump sum before this age, the amount will be adjusted to reflect the earlier payout, typically resulting in a lower lump sum due to the longer period the funds are expected to last.
-
How does the covered compensation offset affect my pension benefit under the Final Average Pay and Annual Accumulation plans?
The covered compensation offset reduces your pension benefit by a portion related to the Social Security Wage Base. This offset is intended to coordinate your pension benefits with Social Security benefits, reducing the pension by a percentage of your covered compensation.
-
Can I change my pension plan election after I have chosen one?
Generally, once you make an election between the different pension plans during an open choice window (such as the healthcare companies Retirement Choice program), your decision is irrevocable. Future accruals will be based on the selected plan unless there is another choice opportunity provided by the employer.
Understanding these elements of the healthcare companies Pension Plan will help you navigate your retirement benefits effectively. Always consult the plan administrator or HR for personalized advice and the latest information.
Lump-Sum vs. Annuity
Retirees in your city, your state who are eligible for a pension are often offered the choice of whether to actually take the pension payments for life, or receive a lump-sum dollar amount for the “equivalent” value of the pension – with the idea that you could then take the money (rolling it over to an IRA), invest it, and generate your own cash flows by taking systematic withdrawals throughout retirement from your company.
The upside of keeping the pension itself is that the payments are guaranteed to continue for life (at least to the extent that the pension plan itself remains in place and solvent and doesn’t default). Thus, whether you live 10, 20, or 30 (or more!) years after leaving your company, you don’t have to worry about the risk of outliving the money.
In contrast, selecting the lump-sum gives you the potential to invest, earn more growth, and potentially generate even greater retirement cash flow. Additionally, if something happens to you, any unused account balance will be available to a surviving spouse or heirs. However, if you fail to invest the funds for sufficient growth, there’s a danger that the money could run out altogether and you may regret not having held onto the pension’s “income for life” feature.
Ultimately, the “risk” assessment that should be done to determine whether or not you should take the lump sum or the guaranteed lifetime payments that your company pension offers depends on what kind of return must be generated on that lump-sum to replicate the payments of the annuity. After all, if it would only take a return of 1% to 2% on that lump-sum to create the same pension cash flows for a lifetime, there is little risk that you will outlive the lump-sum after leaving your company, even if you withdraw from it for life(10). However, if the pension payments can only be replaced with a higher and much riskier rate of return, there is, in turn, a greater risk those returns won’t manifest and you could run out of money.
Interest Rates and Life Expectancy
In many defined benefit plans, current and future retirees in your city, your state are offered a lump-sum payout or a monthly pension benefit. Sometimes these plans have billions of dollars worth of unfunded pension liabilities, and in order to get the liability off the books, your company may offer a lump-sum.
Depending on life expectancy, the initial lump-sum is typically less money than regular pension payments over a normal retirement time frame. However, most individuals that opt for the lump-sum plan to invest the majority of the proceeds, as most of the funds aren't needed immediately after retirement from your company.
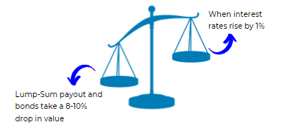
Something else to keep in mind is that current interest rates, as well as your life expectancy at retirement age retirement age, have an impact on lump-sum payout options of your company's defined benefit pension plans. Lump-sum payouts are typically higher in a low interest rate environment, but be careful because lump-sums decrease in a rising interest rate environment.
Additionally, projected pension lump-sum benefits for active corporate employees will often decrease as an employee ages and their life expectancy decreases. This can potentially be a detriment of continuing to work, so it is important that you run your pension numbers often and thoroughly understand the impact that timing has on your benefit. Other factors such as income needs, need for survivor benefits, and tax liabilities often dictate the decision to take the lump-sum over the annuity option on the pension.
Over half of plan participants admit they don’t have the time, interest, or knowledge needed to manage their 401(k) portfolio. But the benefits of getting help goes beyond convenience. Getting help may make it easier to build a diversified portfolio and stick with it through market swings. 
Getting help can be the key to better results across the 401(k) board.
A major retirement-plan provider study found several positive outcomes common to those using independent professional advice. They include:
- Improved savings rates – 70% of participants who used 401(k) advice increased their contributions.
- Increased diversification – Participants who managed their own portfolios invested in an average of just under four asset classes, while participants in advice-based portfolios invested in a minimum of eight asset classes.
- Increased likelihood of staying the course – Getting advice increased the chances of participants staying true to their investment objectives, making them less reactive during volatile market conditions and more likely to remain in their original 401(k) investments during a downturn. Don’t try to do it alone.
Get help with your company's 401(k) plan investments. Your nest egg will thank you.
Net Unrealized Appreciation (NUA)
When you qualify for a distribution, you have three options:
- Roll-over your qualified plan to an IRA and continue deferring taxes.
- Take a distribution and pay ordinary income tax on the full amount.
- Take advantage of NUA and reap the benefits of a more favorable tax structure on gains.
How does Net Unrealized Appreciation work?
First an employee must be eligible for a distribution from their qualified company-sponsored plan. Generally, at retirement or age 59 1/2, the employee takes a 'lump-sum' distribution from the plan, distributing all assets from the plan within one tax (calendar) year. The portion of the plan that is made up of mutual funds and other investments can be rolled into an IRA for further tax deferral. The highly appreciated company stock is then transferred to a non-retirement account.
The tax benefit comes when you transfer the company stock from a tax-deferred account to a taxable account. At this time, you apply NUA and you incur an ordinary income tax liability on only the cost basis of your stock. The appreciated value of the stock above its basis is not taxed at the higher ordinary income tax but at long-term capital gains rates of 0%, 15%, or 20%, depending on your taxable income. Depending on your tax brackets, this could mean meaningful tax savings on the appreciation.
As a corporate employee in your city, your state, you may be interested in understanding NUA from a financial advisor.
IRA Withdrawal
When you qualify for a distribution, you have three options:
Your retirement assets may consist of several retirement accounts: IRAs, 401(k)s, taxable accounts, and others.
So, what is the most efficient way to take your retirement income after leaving your company?
You may want to consider meeting your income needs in retirement by first drawing down taxable accounts rather than tax-deferred accounts.
This may help your retirement assets with your company last longer as they continue to potentially grow tax deferred.
You will also need to plan to take the required minimum distributions (RMDs) from any company-sponsored retirement plans and traditional or rollover IRA accounts.
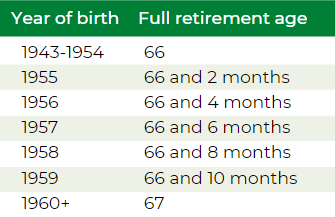
IRS rules require you to begin taking distributions from these types of accounts when you reach your RMD age: 73 if you were born from 1951 through 1959, or 75 if you were born in 1960 or later. Beginning in 2023, the excise tax for every dollar of your RMD under-distributed is reduced from 50% to 25%.
Current rules allow account owners to delay taking their first RMD until April 1 following the later of the calendar year they reach RMD age or, in a workplace retirement plan, retire.
Two flexible distribution options for your IRA
When you need to draw on your IRA for income or take your RMDs, you have a few choices. Regardless of what you choose, IRA distributions are subject to income taxes and may be subject to penalties and other conditions if you’re under 59½.
Partial withdrawals: Withdraw any amount from your IRA at any time. If you’re 73 or over, you’ll have to take at least enough from one or more IRAs to meet your annual RMD.
Systematic withdrawal plans: Structure regular, automatic withdrawals from your IRA by choosing the amount and frequency to meet your income needs after retiring from your company. If you’re under 59½, you may be subject to a 10% early withdrawal penalty (unless your withdrawal plan meets Code Section 72(t) rules).
Your tax advisor can help you understand distribution options, determine RMD requirements, calculate RMDs, and set up a systematic withdrawal plan.
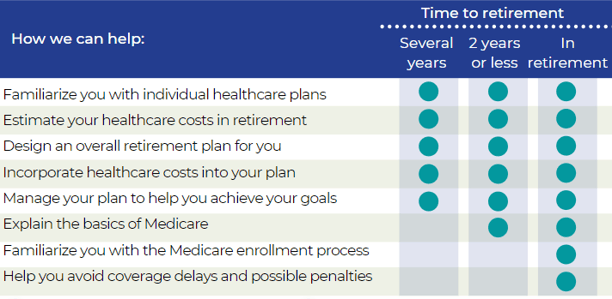
You and your Medicare-eligible dependents must enroll in Medicare Parts A and B when you first become eligible. Many company-sponsored retiree medical plans pay benefits as if Medicare Parts A and B paid first, whether or not you actually enroll, so check your company's plan for its rules.