<img height="1" width="1" style="display:none" src="https://www.facebook.com/tr?id=314834185700910&amp;ev=PageView&amp;noscript=1">

Retirement Guide for PG&E Employees

2027 Tax Rates & Inflation

In this comprehensive retirement guide for PG&E employees, we cover the most critical factors to take into account when deciding on the optimal time to retire from PG&E.

From tax rates and health care to inflation, and beyond, this guide is designed to answer you most pressing retirement questions.

While we are not affiliated with PG&E, The Retirement Group has extensive experience working with PG&E employees as they move toward and into retirement. Feel free to reach out to us with any questions you have  about the information in this guide. For additional details, we recommend reaching out to your PG&E benefits department.

2027 Tax Changes & Inflation

tax-changes-inflation-pge-guide

Each year the IRS adjusts tax brackets, deductions and retirement plan limits for inflation. These are the 2027 changes most likely to matter to employees who are approaching retirement:

  • For 2027, the standard deduction is $16,600 for single filers and married individuals filing separately, $33,200 for married couples filing jointly, and $24,925 for heads of household.
  • Taxpayers who are 65 or older, or blind, can add $1,700 to their standard deduction for 2027 if married, or $2,100 if single or head of household.
  • For tax years 2025 through 2028, taxpayers age 65 or older may also claim a separate senior deduction of up to $6,000 each ($12,000 for a married couple filing jointly when both spouses qualify). It phases out above $75,000 of modified adjusted gross income ($150,000 for joint filers) and is available whether or not you itemize.

The personal exemption remains at $0. The One, Big, Beautiful Bill Act made that change permanent.

Retirement account contributions: Pre-tax contributions to your employer's 401(k) plan may help reduce your taxable income. For 2027, employees can contribute up to $25,500 to 401(k), 403(b) and most 457 plans. Employees age 50 and over can add a catch-up contribution of up to $8,500, and employees age 60 through 63 may be able to make a higher catch-up of up to $11,750 if their plan allows it. If your 2026 Social Security wages from the employer sponsoring your plan were above $155,000, any 2027 catch-up contributions must be made as Roth (after-tax) contributions. The IRA contribution limit for 2027 is $7,500, plus a catch-up amount for those age 50 and over.

Charitable deduction for non-itemizers: Beginning with tax year 2026, taxpayers who take the standard deduction may deduct up to $1,000 ($2,000 joint) of cash gifts to eligible charities. Gifts to donor-advised funds and non-cash gifts do not qualify.

Child Tax Credit: For 2027, the Child Tax Credit is up to $2,300 per qualifying child. The credit begins to phase out above $200,000 ($400,000 joint) of modified adjusted gross income.

Remote work and state taxes: If you work remotely in a different state from your employer's office, you may owe tax in more than one state. Some states, including New York, apply a "convenience of the employer" rule that can tax a remote employee's wages as if the work were done in that state. A tax advisor can help you review whether credits or other options apply to your situation.

2027 Federal Income Tax Brackets

RateSingleMarried Filing JointlyMarried Filing SeparatelyHead of Household
10%$0 - $12,800$0 - $25,600$0 - $12,800$0 - $18,250
12%$12,801 - $52,025$25,601 - $104,050$12,801 - $52,025$18,251 - $69,650
22%$52,026 - $109,125$104,051 - $218,250$52,026 - $109,125$69,651 - $109,100
24%$109,126 - $208,325$218,251 - $416,650$109,126 - $208,325$109,101 - $208,300
32%$208,326 - $264,550$416,651 - $529,100$208,326 - $264,550$208,301 - $264,550
35%$264,551 - $661,375$529,101 - $793,650$264,551 - $396,825$264,551 - $661,350
37%$661,376+$793,651+$396,826+$661,351+

Source: IRS Rev. Proc. 2026-35, section 3.01, Tables 1-4 (IR-2026-133, November 5, 2026).

Inflation reduces purchasing power over time, so the same goods and services cost more as prices rise. Social Security benefits rise 3.6% in January 2027 through the annual cost-of-living adjustment. When building a retirement income plan, consider inflation assumptions, Medicare premiums, prescription drug costs and other health care expenses alongside the 2027 tax brackets and deductions above. For 2027, the standard Medicare Part B premium is $209.40 a month and the annual deductible is $292. The Part A inpatient hospital deductible is $1,776 per benefit period. Hospital coinsurance is $444 a day for days 61 through 90 and $888 a day for lifetime reserve days. Skilled nursing facility coinsurance is $222 a day for days 21 through 100. Out-of-pocket spending on covered Part D drugs is capped at $2,400.

Sources: IRS, Social Security Administration, Centers for Medicare & Medicaid Services.

Schedule An Appointment with a Retirement Group Advisor


Please choose a date that works for you from the available dates highlighted on the calendar.


Planning for a Layoff or Job Change at PG&E

Blogs You May Enjoy

New call-to-action

New call-to-action

New call-to-action

additional-articles-trg

Planning Your Retirement

planning-retirement-pge-guide

Retirement may seem like something too far away—or too complicated—to worry about today. But it's important to remember that retirement "planning" is a verb, underscoring the need to take consistent action whether you’re 20 or 60.

The reality is that most Americans don’t know how much to save or the amount of income they’ll need in retirement.

No matter where you stand in the planning process, or your current age, we designed this guide to provide you with a comprehensive overview of the steps you can take toward retirement. With the right resources, you can simplify and streamline your transition from PG&E into retirement, and get the most from your benefits in your city your state.

You know you need to be saving and investing, because "time in the market" beats "timing the market". But even if you've been investing for years, the game changes entirely once you switch from saving to spending.

That's where The Retirement Group comes in. We've partnered with Wealth Enhancement to offer a wide range of retirement planning resources. With a qualified, competent, and caring advising team by your side, PG&E employees in the United States can make the most of what they've saved, and better plan for what they still need.

"Russell Investments' annual Value of an Advisor study suggests that much of an advisor's potential value comes from behavioral coaching, tax-aware planning and personalized wealth planning, not from picking investments."

Source: Is it Worth the Money to Hire a Financial Advisor?, The Balance, 2021


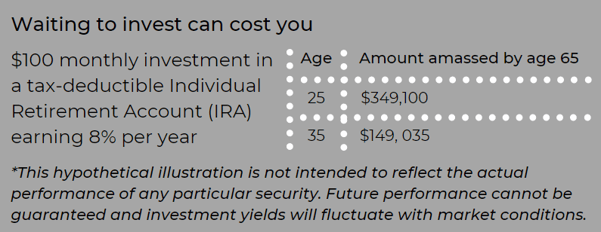
Starting to save as early as possible matters. Time on your side means compounding can have significant impacts on your future savings. And, once you’ve started, continuing to increase your 401k contributions and making the most of any company match is key.

ATTV5 Graph page8

Did you know?

Investing consistently in your company's retirement plan over many years, and contributing enough to receive the full employer match, may help your savings grow by the time you retire.

*Source: Bridging the Gap Between 401(k) Sponsors and Participants, T.Rowe Price, 2020
As decades go by, you’re likely full swing into your career at PG&E, and your income probably reflects that. However, the challenges to saving for retirement start coming from large competing expenses: a mortgage, raising children, and saving for their college.

One of the classic planning conflicts is saving for retirement versus saving for college. Most financial planners will tell you that retirement should be your top priority because your child can usually find support from financial aid while you’ll be on your own to fund your retirement.

The amount you invest toward retirement should always be based on your unique financial situation and goals. However,  a good rule of thumb is to consider investing a minimum of 10% of your salary toward retirement through your 30s and 40s, while aiming to receive your employer's full contribution match, as long as your individual circumstances allow it.

Over 50? In 2027 you can invest up to $34,000 into your retirement plan/401k, which consists of the individual contribution limit of $25,500 plus the over-50 catch-up contribution of $8,500.

As you enter your 50s and 60s, you’re ideally at peak earning years with some of your major expenses, such as a mortgage or child-rearing, behind you or soon to be in the rearview mirror. This can be a good time to consider if you can boost your retirement savings goal to 20% or more of your income. For many people, this could potentially be the last opportunity to stash away funds.

Why are 401ks and matching contributions so popular?

401ks are powerful tools for your retirement savings plan. They provide three main opportunities:

  • Compound growth opportunities (as evidenced by the example above)
  • Tax saving opportunities
  • Matching contributions

Matching contributions are just what they sound like: Your company matches your own personal 401k contributions up to a specified amount or percentage, using corporate funds.

For example, for employees hired on or after January 1, 2013, PG&E matches 75% of contributions up to 8% of pay. If your salary is $100,000 and you invest $8,000 in your 401k, PG&E would add $6,000, resulting in a $14,000 increase to your 401k balance. If you invested $10,000 instead, PG&E would still add $6,000, bringing your total 401k investment to $16,000 for that year.
Unfortunately, many people don’t take full advantage of their employer match because they’re not meeting the minimum contribution requirement.
 
For example, if you were hired on or after January 1, 2013, PG&E matches 75% of your contributions up to 8% of pay, so if you only contribute 4% of your salary, you aren't getting the full amount of your match. By raising your contribution to 8%, you would receive PG&E's full match of 6% of pay, for a total combined employee and employer contribution of 14% of your salary. By doing so, you aren’t leaving money on the table.
 
Employees who don't contribute enough to receive their full company match leave part of that match unclaimed each year, and over a career the missed amounts can add up.
If you want to make the most of the retirement savings opportunities PG&E offers before you retire, reach out today to schedule a call with The Retirement Group.
Schedule a Call

Your Pension Plan

BOE-HTML-Your-Pension-Plan

Whether you’re changing jobs or retiring, knowing what to do with your hard-earned retirement savings can be difficult. An employer-sponsored pension plan may make up the majority of your retirement savings, but how much do you really know about that plan and how it works?

There are seemingly endless rules that vary from one plan to the next, early out offers, interest rate impacts, age penalties, and complex tax implications.

Growing your investment balance and managing taxes are key to a successful retirement plan spending strategy. At The Retirement Group, we can help you understand how your pension fits into your overall financial blueprint.

"Getting help and leveraging the financial planning tools and resources your company makes available can help you understand whether you are on track, or need to make adjustments to meet your long-term retirement goals..."

Source: Schwab 401(k) Survey Finds Savings Goals and Stress Levels on the Rise

Understanding the PG&E Pension Plan 

If you have a monthly annuity and you start your pension on your retirement date, your first monthly pension payment will be made on the first of the month after you retire—not on your retirement date—and your first payment will include your first and second monthly benefits. The way your pension is calculated depends on the type of formula you have and your employment classification.

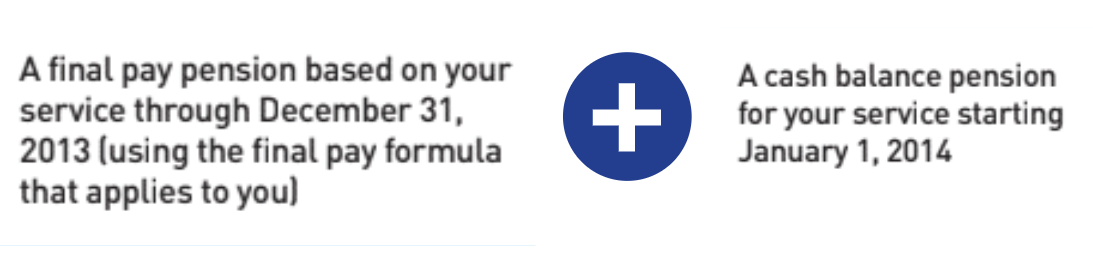
  • Employees hired before 2013 may have the final pay formula—or a combination of the final pay formula and the cash balance formula.
  • All employees hired in 2013 and later have the cash balance formula.

Cash Balance Formula & Annual Pay Credits

Cash Balance Formula
The cash balance formula lets your pension benefit accumulate for each year you work in a pension-eligible position—not just at the end of your employment.

All employees hired 2013 and later, or employees hired before 2013 that chose the cash balance formula, can accrue annual pay credits based on full years of age and full years of credited service. Plus, your account is credited with interest on the last day of each calendar quarter.

Annual pay credits
Annual pay credits are based on a point system of full years of age and full years of credited service as of December 31 each year:


Example:

55 years old + 21 years of service = 76 points (55 + 21). This person would get an annual pay credit of 9% of pay.

Annual pay credits based on points (age + service):

Fewer than 40 points

5% of pay
40-49 points 6% of pay
50-59 points 7% of pay
60-69 points 8% of pay
70-79 points 9% of pay
80 or more points 10% of pay


If you have both formulas:

Did you choose the cash balance formula during the pension choice period in 2013? You'll have:

You can start your two benefits at the same time or separately, and you can make the same or different payment option and joint pensioner elections for the two benefits.


Retiring Early?

The younger you are when you retire, the more your benefit may be reduced to reflect what’s likely to be a longer retirement period.

Final Pay Formula Cash Balance Formula
If you start to receive your monthly pension payments before age 65, your benefit may be reduced. No matter how old you are when you leave PG&E, you can take your vested cash balance benefit as a single lump-sum payment or as a monthly annuity for life.
Any reductions in your monthly pension benefit will be based on your years of credited service and age when your pension payments begin.* If you take your cash balance benefit as a lump sum, you can roll it into another retirement plan--like an IRA--to avoid potential immediate income taxes or IRS early withdrawal penalties.
Your personalized pension election form already shows reduced benefits if the early retirement reduction factors apply to you. If you take your cash balance benefit as an annuity, your account balance will be converted to a monthly benefit for life using IRS-based actuarial factors that take into account your age when you start receiving benefits.

* The final pay formula's early retirement reduction factors are calculated using bands of service years, as described in the Summary of Benefits Handbook.


Pension payments can’t be changed or stopped:

After you start receiving your monthly pension payments, they’ll continue for life.

  • You can’t change any of your pension elections for any reason after your pension start date.

  • Your payments can’t be stopped or suspended even if you’re rehired or reinstated by PG&E, unless there is a legal reason requiring a hold on your pension benefit.

Delaying your Pension

Planning a new career after you retire? Have a new job lined up?

You can delay the start of your pension, whether you have the final pay formula or the cash balance formula. You’re not required to start your pension to receive retiree medical coverage, and you’re not required to elect retiree medical coverage to receive your pension. If you delay your pension, you’ll still be considered a retiree for all your other retirement benefits.

Starting a delayed pension: If you decided to delay your pension when you retired and you later want to start your pension, you must notify the PG&E Pension Call Center at least 90 days but no more than 180 days before you want your pension to start. If you’re retiring early and you delay the start of your pension, your benefit may increase.

Final pay formula
Do you have an early retirement reduction? It will decrease for every month that you delay the start of your monthly pension payments, until you qualify for an unreduced pension. The later you start your pension payments, the smaller the reduction for early retirement.

Example: Delayed pension for employee with 20 years of service

Payment Starts Benefit at normal retirement age (single life pension) Early retirement reduction factor Early retirement benefit (single life pension)
Age 55 $1,000 per month

26%

$740 per month
Age 60 $1,000 per month 6% $940 per month
Age 62 $1,000 per month 0% $1,000 per month
Age 65 $1,000 per month 0% $1,000 per month


If you come back to work for PG&E

If you’re rehired or reinstated by PG&E:

  • - You’ll keep your pension.
  • - Any monthly annuity payments will continue while you work.
  • - You’ll earn income as an active employee.

Benefits for pension-eligible rehires:

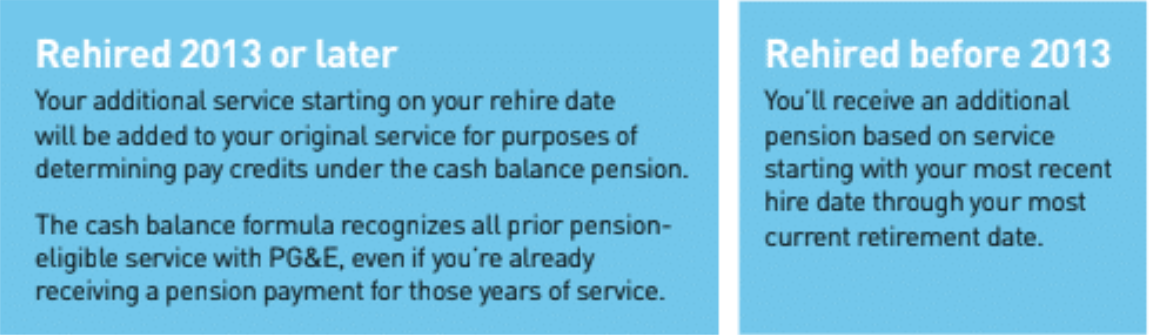
If you’re rehired as a pension-eligible employee, you’ll be eligible for a new pension benefit under the cash balance formula as if you were a newly hired employee—except you’ll be immediately vested. The new cash balance benefit will be added to your unchanged original pension payment after you retire a second time.

Did you contribute to the Retirement Plan before 1973?

Check your personalized Pension Election and Authorization form. It will show your contributions if you made any.
If you made contributions, you need to decide what to do with them:

When do you want your refund?

You can get your refund in the same year as your first pension payment (your pension start date) or in the next year after your pension start date.

Refund election dates are tied to your pension start date—not to your retirement date. If your pension is delayed, your refund will also be delayed. Here are your choices:

Current-year refund

  • Refund will be paid in the same year as your pension start date
  • Refund will be paid in the same month as your first pension payment
  • Refund may be paid on a different date than your first pension payment

Next-year refund

  • Refund will be paid the year after your pension start date
  • Refund will be paid in January of the following year
  • Refund may be paid on a different date than your January pension payment

How do you want your refund?

You have three payment options for your refund:

Taxes and timing of your refund

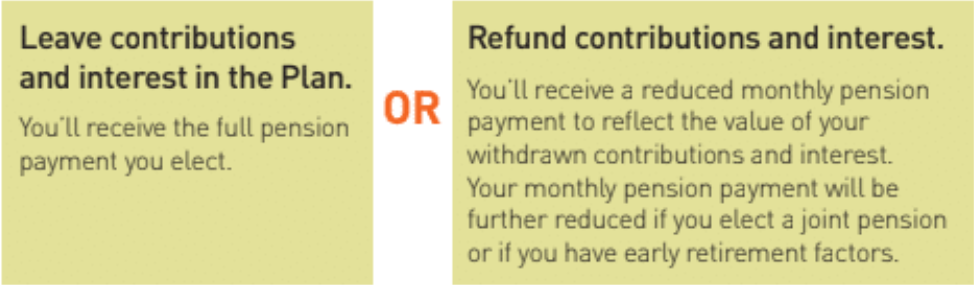
Your contributions were made on an after-tax basis, but the interest you accrued has been tax-deferred. Federal laws require that you receive the credit for your non-taxable contributions over your expected lifetime.

This means if you get a refund now, most of the refund will be taxable in the year you receive it.

Even if you don’t get a refund of your contributions, your monthly pension payment will contain a portion that is not taxable until either:

  • - The full value of your after-tax contributions has been returned to you, if you don’t get a refund.
  • - The full value of your after-tax contributions has been accounted for, if you do get a refund.

If you’re married

If you die before your entire contribution is returned to you or is fully accounted for, your spouse will be able to deduct the remaining non-taxable portion from your tax return for the year in which you die.

If you live past the life expectancy used in your benefit calculation, then your full pension payment will be taxable after you have received your entire contribution or after it has been fully accounted for.


Refunds and rollovers

Most of your cash refund will be taxable in the year you receive it. PG&E will withhold required taxes from your cash refund.

The rollover amount won’t be taxable until you withdraw the money from your tax-qualified plan. No taxes will be withheld from the direct rollover of your interest as long as you complete the rollover within 60 days of the date on your rollover check. If you’re late delivering the rollover funds, you may have immediate income taxes and IRS early withdrawal penalties on the amount of your rollover.


Annuity options

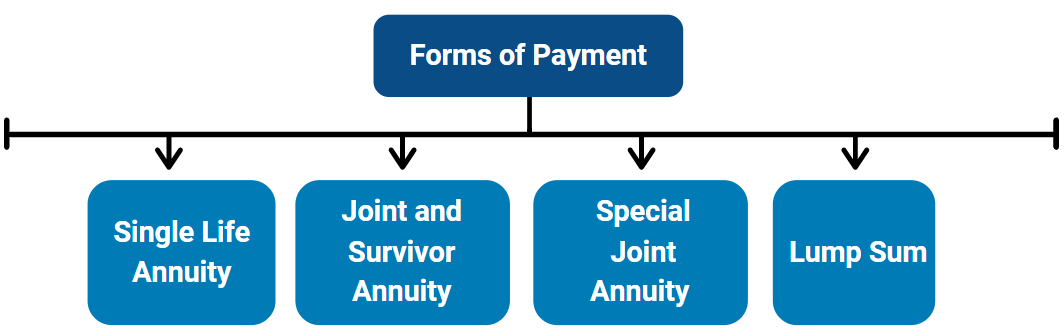
Both the final pay formula and the cash balance formula allow the following monthly annuities. You can be single or married to elect any of these options:

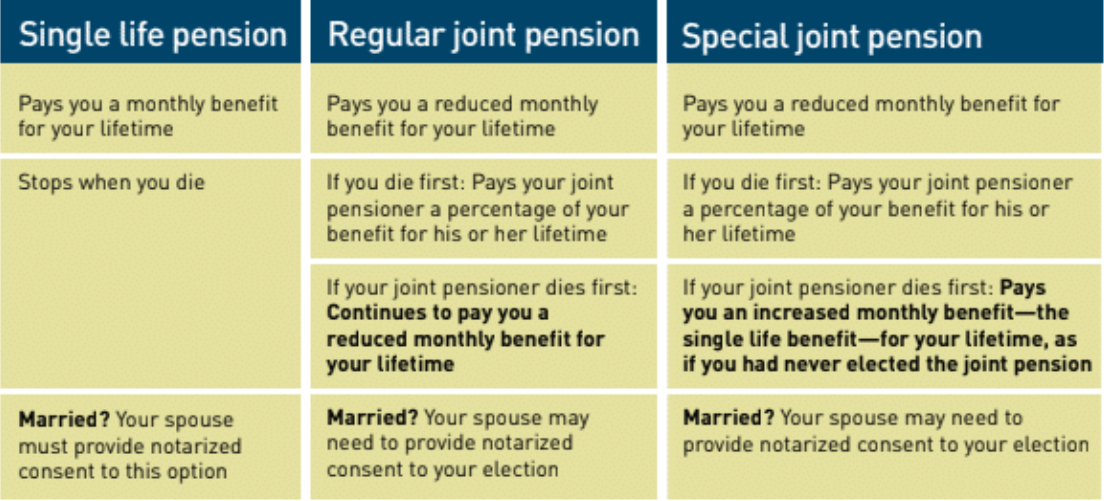
Single life pension

This option pays you a monthly benefit for your lifetime and stops the first of the month after your death. No payment will be made to any other person after your death.

If you elect this option, you won’t be able to change your election even if you later marry or want to add a joint pensioner other than your spouse.


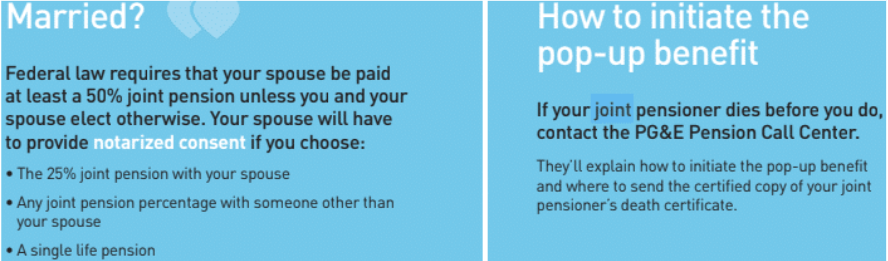
Married?

Federal law requires that your spouse be paid at least a 50% joint pension unless you and your spouse elect otherwise. Your spouse will have to provide notarized consent if you choose the single life pension.


Regular joint pension

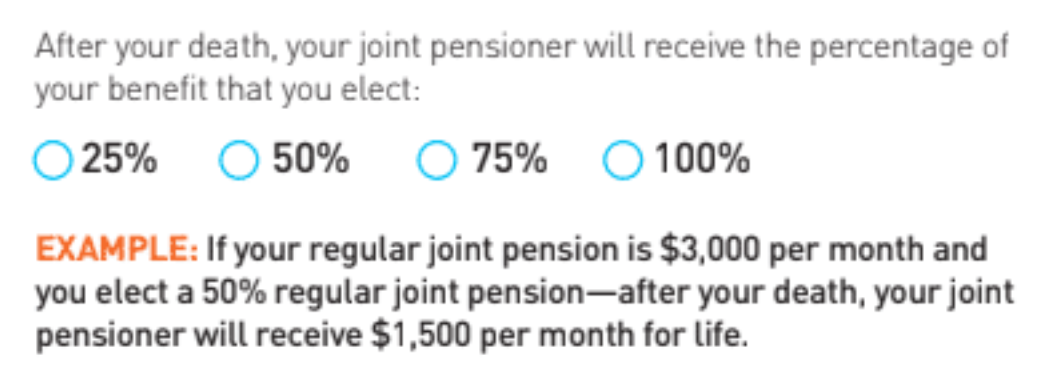
This option pays you a reduced monthly benefit (compared to a single life pension) for your lifetime—plus, after your death, it pays a further benefit to any one person you choose for his or her lifetime. Your basic monthly pension benefit will be reduced to reflect the additional value of this option to your joint pensioner.

Your percentage options may be limited if your joint pensioner isn’t your spouse and is more than 10 years younger than you are.

If your joint pensioner dies before you do, your benefit will continue as the reduced monthly pension payment for your lifetime. No payment will be made to anyone after your death.


Special joint pension

This option pays you a reduced monthly benefit (compared to a single life pension and a regular joint pension) for your lifetime—plus, after your death, it pays a further benefit to any one person you choose for his or her lifetime.

If your joint pensioner dies before you do, your benefit will increase or “pop up” to the original single life pension benefit—as if you had never elected a joint pension. This increased benefit will be payable for your lifetime, but no payments will be made to anyone after your death.

Your basic monthly pension benefit will be reduced by more than it would for the regular joint pension. That’s because this option offers greater value to you if your joint pensioner dies first. If you die first, your joint pensioner’s monthly benefit won’t increase beyond the percentage you elect.


You can't change your joint pensioner

If you elect a joint pension, the person you designate as your joint pensioner will be the only person to receive the joint survivor’s benefit when you die.

You won’t be able to designate a different joint pensioner to receive your survivor’s benefit—and you won’t be able to remove the joint pensioner you elect. This rule applies even if:

  • You later divorce or sever ties with your joint pensioner
  • You later marry a new spouse
  • Your joint pensioner dies


Relative Value of Joint Pension Options

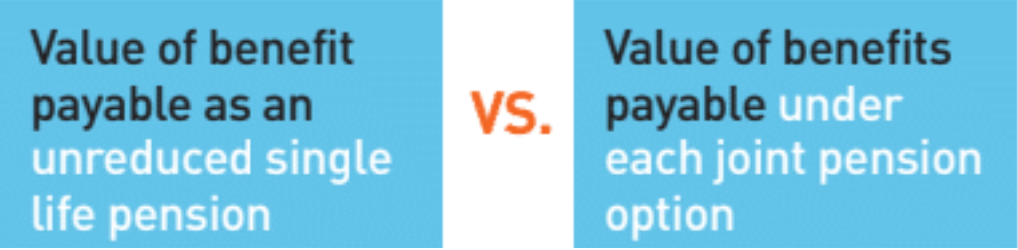
Your personalized pension benefit estimate shows a relative value percentage for each of the joint survivor’s pension options, so you can compare:

The relative values are determined using interest rates and life expectancy assumptions specified by the IRS. The relative value compares the actuarial equivalent of your unreduced single life pension to each joint pension option amount based on the life expectancy of you and your joint pensioner.

If you or your joint pensioner live longer than the assumptions, the actual value of your lifetime payments will be greater than the stated value because you’ll receive the payments for a longer period of time.


Thinking about what to do with your pension is an important part of planning for your retirement from PG&E. What is best for you and your family?

You should routinely use the tools and resources found in The Retirement Group's e-book library, such as the RetireKit, to model your pension benefit in retirement and the pension payment options that will be available to you.

You can also contact a PG&E advisor at The Retirement Group at (800) 900-5867. We will get you in front of an advisor knoweldgeable about your plan to help you start the retirement process and better understand how your payments work .

Note: We recommend you read the PG&E Summary Plan Description. The Retirement Group is not affiliated with PG&E. 

Next Steps:

  • Consider how interest rates affect your decision.

  • Use the "RetireKit" to explore cash flow, interest rates, and which pension option might be the best fit for you during retirement.

  • As you get closer to your retirement date, contact a retirement-focused advisor at The Retirement Group and read the applicable SPD Summary to start your retirement process.

  • PG&E will need you to provide documents that show proof of birth, marriage, divorce, Social Security number, etc., for you and your spouse/legally recognized partner.

  • PG&E has Beneficiary Designation forms online that allow you to update your beneficiary designations, if applicable to your pension program. Please read your SPD for more details.

Interest Rates and Life Expectancy

In many defined benefit plans, current and future retirees are given a choice to either receive pension payments for life or take a lump sum dollar amount upfront for the "equivalent" value of the pension. At PG&E, the lump sum is available for the cash balance benefit; the final pay benefit is paid only as a monthly annuity.

Deciding which option is right for you will depend on prevailing interest rates, your income needs, the need for survivor benefits, anticipated tax liabilities, and more.

For instance, while annuity payouts are typically lower in a low interest rate environment, they tend to increase when rates rise. Additionally, projected pension annuity benefits for active employees will often decline as an employee ages and their life expectancy decreases. This may influence your retirement timing.

Given the number of factors to take into account, it's important to run your pension numbers often to be sure the decisions you make are right for you and your family. 

Optimizing Your Pension Payout

BOE-HTML-Your-Pension-Plan

As retirement approaches, you may find  yourself wondering whether a pension lump sum or a lifetime annuity is right for you. The choice you make will have a significant impact on your retirement planning and influence your post-retirement lifestyle. By meeting with a financial advisor in advance, you can get the guidance you need to tailor your financial strategies to your personal objectives.

One way to potentially get more from your pension is by opting to receive a single life annuity and using the difference between this payout and that of a joint and survivor annuity to purchase a life insurance policy. Given that single life annuities have a higher payout than joint and survivor annuities, choosing a single life annuity will provide a higher monthly return while the pension holder lives, after which the life insurance policy will continue providing a payout for the pension holder's spouse or family.


Benefits and Drawbacks of Backstopping Your Annuity with Insurance

Benefits:

  1. Higher monthly pension income: A Single Life Annuity pays the highest monthly income of the pension options, and using a portion of that income for a life insurance policy may create a payout for your loved ones.
  2. You give yourself inheritance flexibility: In the case that you outlive your spouse, you are at liberty to designate your life insurance payout to other family members. 
  3. Generally income-tax-free payment: When your spouse (or children) receives the life insurance death benefit, it is generally free of federal income tax. Life insurance death benefits are generally excluded from income tax, unlike pension annuity payouts which are treated as taxable income no matter who receives them.

Drawbacks:

  1. Potential loss of pension benefits: While Single Life Annuities tend to offer higher monthly payments, you may lose medical or other benefits if your employer offers them through a pension plan you did not elect.
  2. Lackluster life insurance payouts: With life insurance payouts being a central component of this strategy, less-than-anticipated payouts may or may not steer you away from this financial route.
  3. Insurance policies lapse, while pensions don’t: With life insurance at the center of this strategy, forgetting to renew your policy or pay monthly premiums can be a costly mistake. On the other hand, most private pension plans in the U.S. are insured, up to legal limits, by the Pension Benefit Guaranty Corporation.

Overall, this strategy may be useful for those who are in good health, have a longer life expectancy, and want to provide for their loved ones after their own passing. On the other hand, individuals in a later stage of life or in poor health may not fully benefit from this strategy. Regardless of your situation, a financial advisor can help you decide whether or not this financial strategy is right for you.

Your 401k Plan

US-Bank-HTML-Your-401k-Plan

Professional help is available

Not sure what to do with your Retirement Savings Plan (RSP) account? Please call The Retirement Group at (800) 900-5867 for more information and we can get you in front of a PG&E-focused advisor. Details on your RSP will be in the distribution package from your plan administrator, and you can find more information by logging on to your account at 401k.com or in the Summary of Benefits Handbook via mypgebenefits.com > Resources tab. If you are from your city, your state, and are in the retirement age category, our advisors are particularly equipped to tailor advice for your situation.

Company Match

Management and A&T Employees

The Retirement Savings Plan for Management and A&T employees offers two company matching benefits.

 * 75% on contributions up to 6% of pay if you are a participant in the Final Average Pay Pension formula, or 

 * A higher 401k company match of 75% on contributions up to 8% if you are a participant in the Cash Balance Pension.

Union Represented Employees

The Retirement Savings Plan for Union Represented Employees offers two company matching benefits as well.

 * A company match of 60% on contributions up to 3% (with 1 - 3 years of service) or 6% (with 3+ years of service), or

 * a 75% match on contributions up to 8% of pay if the employee is a participant in the Cash Balance Pension.

Vesting

100% of your 401k contributions vest immediately, including all company matching contributions.

Check your beneficiary

Do you still have the right beneficiary for your RSP account? Review your beneficiary designation whenever you experience a significant life event like retirement, marriage, divorce, or the death of a previously designated beneficiary. You can change your beneficiary anytime. Log on to NetBenefits at 401k.com or call Fidelity at 1-877-743-4015.

Next Steps:

  • Watch for your Participant Distribution Notice and Special Tax Notice Regarding Plan Payments. These notices will help explain your options and what the federal tax implications may be for your vested account balance in your city, your state.
  • Read through our e-books: "What has Worked in Investing" & "8 Tenets when picking a Mutual Fund".
  • To learn about your distribution options, call The Retirement Group at (800) 900-5867.
  • Review our e-book for more information on "Rollover Strategies for 401ks"

When was the last time you reviewed your 401k plan account or made any changes to it? If it’s been a while, you’re not alone. Many plan participants spend only a few hours a year, or less, researching their 401k investment choices and making account changes.

Part of this comes down to a tendency many people have to try to figure things out on their own. Just think of the Christmas Eve ritual of assembling toys without looking at the instructions or that road trip taken without stopping to ask for directions. But when we’re talking about 401k investing, choosing to go it alone rather than get help can really hurt.

Many plan participants say they don't have the time, interest, or knowledge needed to manage their 401k portfolio. But the benefits of getting help go beyond convenience. Getting help can be the key to better results across the 401k board.

A 2010 Charles Schwab study found several positive outcomes common to those using independent professional advice. They include:

  • Improved savings rates – 70% of participants who obtained 401k advice increased their contributions.
  • Increased diversification – Participants who managed their own portfolios invested in an average of just under four asset classes, while participants in advice-based portfolios invested in a minimum of eight asset classes.
  • Increased likelihood of staying the course – Getting advice raised the odds of participants staying true to their investment objectives, making them less reactive during volatile market conditions and more likely to remain in their original 401k investments during a downturn.

    Don’t try to do it alone. Get help with your PG&E 401k plan investments. Your nest egg will thank you.

Strategies to leverage your 401k before retirement

Did you know that there are ways you can tap into and leverage your 401k funds before retirement? Although these strategies may not apply to every situation, you may be able to use your 401k to bridge certain gaps in your financial plan.


Strategy #1. In-Service Withdrawals and 401k Rollovers

An in-service withdrawal is when an employee takes money from their 401k while they're still employed. In-service withdrawals are a way to access money from your 401k early, and potentially roll it over into a different account type:
 
  1. Eligibility. In-service withdrawals are generally available to employees after they reach age 59 and a half, so they avoid the 10% early withdrawal penalty. However, some plans allow for earlier access to 401k funds under circumstances such as financial hardship.
  2. IRA rollover. These withdrawals are often used to roll over funds into an IRA or another retirement account while you're still employed. A direct rollover can avoid the 10% early withdrawal penalty, as well as any mandatory tax withholding. Rolling over your 401k into an IRA is a popular option for those looking for more control over their retirement savings. While your 401k might limit investment choices, IRAs often offer a broader range of investments.
  3. Tax implications. If your in-service withdrawal is not rolled over into an IRA, you may face income tax on the amount withdrawn.

It’s important to know that certain withdrawals are subject to regular federal income tax and you may also be subject to an additional 10% penalty tax depending on your age.

You can determine if you’re eligible for a withdrawal, and request one, online or by calling the PG&E Benefits Center. Your plan summary outlines more information and possible restrictions on rollovers and withdrawals.

You should also know that the plan administrator reserves the right to modify the rules regarding withdrawals at any time, and may further restrict or limit the availability of withdrawals for administrative or other reasons. All plan participants will be advised of any such restrictions, which apply equally to all PG&E employees.

Strategy #2. Borrowing from your 401k

If you need money quickly due to a job loss, serious health emergency, or other reason, borrowing from your 401k can be an option.

Banks will make you jump through many hoops for a personal loan, and credit cards charge too much interest... If these are the only options for much-needed cash, your 401k balance might start looking like a usable asset.

Unlike an in-service withdrawal, a loan must be paid back. However, they are not taxable (unless you fail to repay them). Yet, despite the potential benefits, taking a loan from your 401k may also come with some drawbacks.

  1. Borrowing from the future. First and foremost, you may be setting your retirement plan back by some time if you take money from your future and use it today.
  2. Lost growth potential. Even though you'll repay the loan, those funds will miss out on potential growth through investments during the repayment period. This can create a gap in your portfolio, especially if the market performs well while your money is out of the account.
  3. Repayment issues. If you leave your employer or lose your job, you may be forced to pay the full loan within a short timeframe. If you're unable to, the loan can be treated as an early withdrawal—and be penalized and taxed as such.

Borrowing from your 401k should be considered a last resort. If you're concerned that you may need to take a loan from your 401k to make ends meet, reach out to an advisor at The Retirement Group today.

Net Unrealized Appreciation (NUA)

When you qualify for a distribution from your 401k plan, you have three options:

  1. Roll over your qualified plan to an IRA and continue deferring taxes.

  2. Take a distribution and pay ordinary income tax on the full amount.
     
  3. Take advantage of NUA and reap the benefits of a more favorable tax structure on gains.

How does Net Unrealized Appreciation work?

NUA is a strategy designed for employees who hold company stock in their retirement plans. 

If that's true for you, you must also be eligible for a distribution from your qualified plan, which typically happens at retirement or age 59 1⁄2. Generally, you would take a lump sum distribution from the plan, distributing all assets from the plan during a one-year period. The portion of the plan that is made up of mutual funds and other investments can be rolled into an IRA for further tax deferral. The highly appreciated company stock is then transferred to a non-retirement account.

The tax benefit comes when you transfer the company stock from a tax-deferred account to a taxable account. At this time, you apply NUA, and you incur an ordinary income tax liability on only the cost basis of your stock. The appreciated value of the stock above its basis is not taxed at the higher ordinary income tax but at the lower long-term capital gains rate, currently 15%. This could mean  potential savings of over 30%.

As a PG&E employee, you may be interested in understanding NUA from a financial advisor.

IRA Withdrawal

Your retirement assets may be spread across several retirement accounts: IRAs, 401ks, taxable accounts, and others. So, what is the most efficient way to take your retirement income? You may want to consider meeting your income needs in retirement by first drawing down taxable accounts rather than tax-deferred accounts. This may help your retirement assets last longer as they continue to potentially grow tax deferred. You will also need to plan to take the required minimum distributions (RMDs) from any employer-sponsored retirement plans and traditional or rollover IRA accounts. That is due to IRS requirements to begin taking RMDs when you reach age 73 (age 75 if you were born in 1960 or later). If you do not, the IRS may assess a 25% penalty on the amount you should have taken.

Two flexible distribution options for your IRA

When you need to draw on your IRA for income or to take your RMDs, you have a few choices. Regardless of what you choose, IRA distributions are subject to income taxes and may be subject to penalties and other conditions if you’re under 59½.

Partial withdrawals: Withdraw any amount from your IRA at any time. If you've reached your RMD age (73, or 75 if you were born in 1960 or later), you'll have to take at least enough from one or more IRAs to meet your annual RMD.

Systematic withdrawal plans: Structure regular, automatic withdrawals from your IRA by choosing the amount and frequency to meet your retirement income needs. If you’re under 59½, you may be subject to a 10% early withdrawal penalty (unless your withdrawal plan meets Code Section 72(t) rules).

Your tax advisor can help you understand distribution options, determine RMD requirements, calculate RMDs, and set up a systematic withdrawal plan. Please consult your attorney or tax advisor for answers to your specific questions. Remember, The Retirement Group is not affiliated with PG&E.

Your Benefits

XOM-HTML-Your-Benefits

HSAs

Health Savings Accounts (HSAs) are often celebrated for their utility in managing health care expenses, particularly for those with high-deductible health plans in your city, your state. However, their benefits extend beyond medical cost management. They also offer a range of retirement saving advantages.

Understanding HSAs

HSAs are tax-advantaged accounts designed for individuals with high-deductible health insurance plans. For 2027, the IRS defines high-deductible plans as those with a minimum deductible of $1,750 for individuals or $3,500 for families. HSAs allow pre-tax contributions, tax-free growth of investments, and tax-free withdrawals for qualified medical expenses—making them a triple-tax-advantaged account.

In 2027, individuals can contribute $4,500 to an HSA and families can contribute $9,000, with an additional $1,000 allowed for those aged 55 and older. Unlike Flexible Spending Accounts (FSAs), HSA funds do not expire at the end of the year; they accumulate and can be carried over indefinitely.

Comparing HSAs to 401ks Post-Matching

Once an employer's maximum match in a 401k is reached, further contributions yield diminished immediate financial benefits. This is where HSAs can become a strategic complement. While 401ks offer tax-deferred growth and tax-deductible contributions, their withdrawals are taxable. HSAs, in contrast, provide tax-free withdrawals for medical expenses, which are often  a significant portion of retirement costs.

HSA as a Retirement Tool

Post age 65, the HSA flexes its muscles as a robust retirement tool. Funds can be withdrawn for any purpose, subject only to regular income tax if used for non-medical expenses. This flexibility is similar to  traditional retirement accounts, but with the added advantage of tax-free withdrawals for medical costs—a significant benefit given the odds of facing rising health care expenses in retirement.

Furthermore, HSAs do not have Required Minimum Distributions (RMDs), unlike 401ks and Traditional IRAs, offering more control over tax planning in retirement. This makes HSAs particularly advantageous for those who might not need to tap into their savings immediately at retirement or who want to reduce their taxable income.

Investment Strategy for HSAs

Initially, it's prudent to invest conservatively within an HSA, maintaining sufficient funds to cover near-term deductibles and other out-of-pocket medical expenses. However, once a financial cushion is established, treating the HSA like a retirement account by investing in a diversified mix of stocks and bonds can enhance the account's growth potential over the long term.

Using HSAs in Retirement

In retirement, HSAs can cover a range of expenses:

  • Health Care Costs-Pre Medicare: HSAs can pay for health care costs to bridge you to Medicare.
  • Health Care Costs-Post Medicare: HSAs can pay for Medicare premiums and out-of-pocket medical costs, including dental and vision, which are often not covered by Medicare.
  • Long-Term Care: Funds can be used for qualified long-term care services and insurance premiums.
  • Non-Medical Expenses: After age 65, HSA funds can be used for non-medical expenses without incurring penalties, although these withdrawals are subject to income tax.

Conclusion

HSAs offer unique advantages that can make them a superior option for retirement savings, particularly after you are contributing enough to receive the full 401k match. Their flexibility in fund usage, coupled with tax advantages, makes HSAs an important consideration when structuring a comprehensive retirement strategy. By strategically managing contributions and withdrawals, individuals can work toward both their medical and financial goals in retirement.


PG&E Benefits Annual Enrollment

As set out in your PG&E SPD, annual enrollment for your PG&E benefits usually occurs each fall. Before it begins, you will be mailed enrollment materials and an upfront confirmation statement reflecting your benefit coverage to the address on file. You’ll find enrollment instructions and information about your benefit options and contribution amounts. You will have the option to keep the benefit coverage shown on your upfront confirmation statement or select benefits that better support your needs. You can choose to enroll in eBenefits and receive this information via email instead.

Next Steps:

  • Watch for your annual enrollment information in the September/November time frame.
  • Review your benefits information and use the tools and resources available on PG&E's Benefits Center website.
  • Enroll in eBenefits.


Things to keep in mind:

  • Many Americans cite health care costs as one of their top financial concerns.
  • Medical bills are a leading contributor to personal bankruptcy in the United States.
  • For older Americans, health care costs represent the second-largest expense, behind housing.


Elected & Automatic Benefits

Elected Benefits
Retiree Medical Coverage*— If you’re eligible

  • Coverage you can elect.
  • A separate packet will be mailed to you with an enrollment form and details about your options.


Retirement service award**

  • A gift you can order within six months of your retirement date at no cost to you.
  • A separate packet will be mailed to you with gift options and a gold card giving you access to PG&E facilities and group discounts.


COBRA***

At your own expense, you can elect COBRA to continue:

  • Dental, vision, EAP, and medical coverage for you and your eligible dependents—for 18 months after you retire.
  • Health Care FSA contributions on an after-tax basis through the end of the calendar year—if you’re enrolled in the FSA when you retire, a separate packet will be mailed to you with costs and forms.

Automatic Benefits

Post-retirement life insurance*

  • Automatically provided at no cost to you.
  • A separate packet will be mailed to you with information about your coverage.


Unused vacation

  • Cash payout in your final pre-retirement paycheck of earned and unused vacation, Paid Time Off, floating holidays, and service anniversary vacation.
  • To avoid having disproportionately high taxes withheld from your final check, ask your supervisor if you can “vacation out” and retire at a later date. 


Unused Health Account Credits*

  • If you’re eligible for PG&E-sponsored retiree medical coverage and you have unused Health Account credits, you can continue to use them—even if you don’t enroll in a PG&E-sponsored retiree medical plan.


Retiree utility discount

  • If you retire from the utility, you’ll continue to get a 25% discount on utility rates as long as you live within PG&E’s service territory and you have a PG&E account in your name.


Short-Term & Long-Term Disability

Short-Term: Depending on your plan, you may have access to short-term disability (STD) benefits.

Long-Term: Your plan's long-term disability (LTD) benefits are designed to provide you with income if you are absent from work for six consecutive months or longer due to an eligible illness or injury.

What happens if your employment with PG&E ends?

Your life insurance coverage and any optional coverage you purchase for your spouse/domestic partner and/or children ends on the date your employment ends, unless your employment ends due to disability. If you die within 31 days of your termination date, benefits are paid to your beneficiary for your basic life insurance, as well as any additional life insurance coverage you elected.

Note:

  • You may have the option to convert your life insurance to an individual policy or elect portability on any optional coverage.

  • If you stop paying supplementary contributions, your coverage will end.

  • If you are at least 65 and you pay for supplemental life insurance, you should receive information in the mail from the insurance company that explains your options.

  • Make sure to update your beneficiaries. See PG&E's SPD for more details.

Beneficiary Designations

As part of your retirement and estate planning, it’s important to name someone to receive the proceeds of your benefits programs in the event of your death. That’s how PG&E will know to whom to send your final compensation and benefits. This can include life insurance payouts and any pension or savings balances you may have.

Next Step:

  • When you retire, make sure that you update your beneficiaries. Your company has an Online Beneficiary Designation form for life events such as death, marriage, divorce, childbirth, adoptions, etc.

If you are unsure about PG&E benefits, schedule a call to speak with one of our PG&E-focused advisors.


Schedule a Call

Social Security & Medicare

NGC-HTML-Social-Security-Medicare

Claiming Social Security is one thing—understanding how your claim works is something else entirely. Understanding Social Security is a difficult but crucial step in assessing your retirement paycheck. For many Americans, Social Security benefits are core to their retirement income strategy. However, when and why you claim them depends on your overall withdrawal strategy.

To help you make an informed decision, let's explore three main steps you should follow to solidify your Social Security strategy at PG&E:

Step 1. Decide when to claim your Social Security benefits

Social Security benefits can be significant, but at the end of the day, they're just one part of your overall financial picture. When considering the timing of your claim, keep this general principle in mind: The later you begin receiving benefits, up to age 70, the larger your monthly benefits will be.

The full monthly Social Security retirement benefit is based on applying at the Full Retirement Age (FRA), which is age 67 for those born 1960 or later. For every year you wait after you reach the FRA, your benefit amount increases 8%. It reaches a maximum at age 70. If we do the math, we can determine that, if you start claiming at age 70, your monthly benefit will be 124% the full benefit.

However, you can also apply before you reach FRA, as early as age 62. Your benefit is permanently reduced if you do so, but this option could make sense for those who want to start claiming their benefit earlier for longevity reasons.
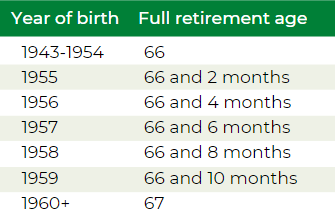
image-png-Nov-04-2021-06-08-27-51-PM

Step 2. Understand the tax implications

For all but the lowest-income retirees, Social Security benefits are actually taxable. Only individuals with provisional income under $25,000, or $32,000 if married filing jointly, receive their benefits tax-free. Otherwise, up to 85% of your benefits will be treated as taxable income.

Furthermore, depending on where you live, your Social Security benefits may even be taxed at the state level. If you plan to move for retirement, the tax regime in the state you're moving to can be a relevant consideration.

Step 3. Start preparing today

Even if your retirement is right around the corner, you can make decisions today that will impact you for years, or decades, to come. For instance, delaying your Social Security claiming date even a year or two can snowball into a significant benefit. To bridge the gap between their retirement date and their claiming date, some people create a "slush fund" while they're working to take the place of the Social Security benefits they would receive from claiming at FRA. Whether these funds come from a 401k, IRA, or brokerage account, integrating a bit of extra padding in your planning can pay off in the long run.

Always remember, your Social Security benefit is just one part of your overall financial picture. And when you start to consider tax implications, withdrawal sequencing, and effective diversification (beyond just the asset class), the picture can start to get complicated. That's what we're here to help with. At The Retirement Group, we've been assisting Chevron employees to and through retirement for years. If you're interested in speaking with an experienced advisor who's been through the process before, reach out today.

Schedule a Call


Medicare Coverage for Retirees

Are you eligible for Medicare or will be soon? If you or your dependents are eligible after you leave PG&E, Medicare generally becomes the primary coverage for you or any of your dependents as soon as they are eligible for Medicare. This will affect your company-provided medical benefits.

It's your responsibility to enroll in Medicare Parts A and B when you first become eligible—and you must stay enrolled to have coverage for Medicare-eligible expenses. This applies to your Medicare-eligible dependents as well.

If you don’t enroll in Medicare Parts A and B, your provider can bill you for the amounts that are not paid by Medicare, which could make your out-of-pocket expenses significantly higher.


If you become Medicare-eligible for reasons other than age, you must contact your company’s benefit center about your status. 
 
You should know how your retiree medical plan choices or Medicare eligibility impact your plan options. Before you retire, contact the U.S. Social Security Administration directly at 800-772-1213, call your local Social Security Office, or visit ssa.gov.


The Reality of Medical Costs in Retirement

According to the Employee Benefit Research Institute (EBRI), Medicare covered about 62% of the cost of health care services for beneficiaries 65 and older in 2023. EBRI's 2026 analysis estimates that a 65-year-old couple with a Medigap plan and median prescription-drug expenses would need $405,000 in savings to have a 90% chance of covering their health care expenses. A single male would need $212,000 and a single female, thanks to her longer life expectancy, would need $252,000.
 
Numbers like these aren't meant to scare you—rather, they're here to inform you about the realities of health care in retirement. A sound retirement income plan, coupled with comprehensive, holistic integration with your overall financial plan, can help you prepare for health care costs after you retire. If you have concerns about your PG&E health care plan or want an experienced set of eyes to look over your options, don't hesitate to reach out. 
 

Divorce

Divorce (graphic)

Divorce later in life has become more common in recent decades, and the ideas of happily ever after and until death do us part don't hold for every couple. Most couples saved together for decades, assuming they would retire together. After a divorce, they face the expenses of a pre- or post-retirement life, but with half their savings.

If you’re divorced or in the process of divorcing, your former spouse(s) may have an interest in a portion of your retirement benefits. Before you can start your pension—and for each former spouse who may have an interest—you’ll need to provide PG&E with the following documentation:

  • A copy of the court-filed Judgment of Dissolution or Judgment of Divorce along with any Marital Settlement Agreement (MSA)
  • A copy of the court-filed Qualified Domestic Relations Order (QDRO)


You’ll need to submit this documentation  to your company’s online pension center regardless of how old the divorce is or how short the marriage is.

For more information on strategies you can use if divorce is affecting your retirement benefits, please give us a call.

Sources: The Retirement Group, “Retirement Plans - Benefits and Savings.”; U.S. Department of Labor, 2024; “Divorced: See how to claim your Social Security benefit,” Fidelity, 2025 

Social Security and Divorce

You can apply for a divorced spouse’s benefit if the following criteria are met:

You’re at least 62 years of age.

You were married for at least 10 years prior to the divorce.

You are currently unmarried.

Your ex-spouse is entitled to Social Security benefits.

Your own Social Security benefit amount is less than your spousal benefit amount, which is equal to one-half of what your ex’s full benefit amount would be if claimed at Full Retirement Age (FRA).

Unlike with a married couple, your ex-spouse doesn’t have to have filed for Social Security before you can apply for your divorced spouse’s benefit, but this only applies if you’ve been divorced for at least two years and your ex is at least 62 years of age. If the divorce was less than two years ago, your ex must already be receiving benefits before you can file as a divorced spouse.
Unlike with a married couple, your ex-spouse doesn’t have to have filed for Social Security
before you can apply for your divorced spouse’s benefit.

Divorce doesn’t even disqualify you from survivor benefits. You can claim a divorced spouse’s survivor benefit if the following are true:

  • Your ex-spouse is deceased
  • You are at least 60 years of age
  • You were married for at least 10 years prior to the divorce
  • You are single (or you remarried after age 60)

In the process of divorcing?

If your divorce isn’t final before your retirement date, you’re still considered married. You have two options:
 
  • Retire before your divorce is final and elect a joint pension of at least 50% with your spouse—or get your spouse’s signed, notarized consent to a different election or lump sum.
  • Delay your retirement until after your divorce is final and you can provide the required divorce documentation.*


Source: The Retirement Group, “Retirement Plans - Benefits and Savings,” U.S. Department of Labor, 2019; “Generating Income That Will Last Throughout Retirement,” Fidelity, 2019

Survivor Checklist

CAT-HTML-Checklist

If you pass away before collecting your retirement benefits, your surviving loved ones must be prepared to take action. It will be their responsibility to collect their survivor benefits. By following the tips in these three sections, you can prepare your loved ones to make the most of the benefits that they're entitled to:


What your survivor needs to do:

  • Report your death. Your spouse, a family member, or even a friend should call your PG&E's benefits service center as soon as possible to report your death.

  • Collect life insurance benefits. Your spouse or other named beneficiary will need to call PG&E's benefits service center to collect life insurance benefits.

If you have a joint pension:

  • Start the joint pension payments. The joint pension is not automatic. Your joint pensioner will need to complete and return the paperwork from your company’s pension center to start receiving joint pension payments.

  • Be prepared financially to cover living expenses. Your spouse will need to be prepared with enough savings to bridge at least one month between the end of your pension payments and the beginning of his or her own pension payments.

If your survivor has medical coverage through PG&E:

  • Decide whether to keep medical coverage.

  • If your survivor is enrolled as a dependent in your company-sponsored retiree medical coverage when you die, he or she needs to decide whether to keep it. Survivors generally pay the full monthly premium; those with a Retiree Medical Savings Account (RMSA) balance can apply it toward the premium cost. If you are retirement age, this decision could significantly impact your financial planning.

Life After Your Career

Life after Retirement (graphic)

While you may be ready for some rest and relaxation, without the stress and schedule of your full-time career, it may make sense to you financially, and emotionally, to continue to work.

Financial benefits of working

Make up for decreased value of savings or investments. Low interest rates may be great for lump sum payouts but they make it harder to generate portfolio income. Some people continue to work to make up for poor performance of their savings and investments.

Maybe you took a company offer and left earlier than you wanted and with less retirement savings than you needed.

Instead of drawing down savings, you may decide to work a little longer to pay for extras you’ve always denied yourself in the past.

Meet financial requirements of day-to-day living.

Expenses can increase during retirement and working can be a logical and effective solution. You might choose to continue working to keep your insurance or other benefits—many employers offer free to low-cost health insurance for part-time workers.

Emotional benefits of working

You might find yourself with very tempting job opportunities at a time when you thought you’d be withdrawing from the workforce.

Staying active and involved.

Retaining employment, even if it’s just part-time, can be a great way to use the skills you’ve worked so hard to build over the years and keep up with friends and colleagues.

Enjoying yourself at work.

Just because the government has set a retirement age with its Social Security program doesn’t mean you have to schedule your own life that way. Many people genuinely enjoy their employment and continue working because their jobs enrich their lives.

PG&E employees interested in planning their retirement may benefit from live webinars hosted by experienced financial advisors. Click here to register for our upcoming webinars for PG&E employees.

Sources

Sources (graphic)6