Each year the IRS adjusts tax brackets, deductions and retirement plan limits for inflation. These are the 2027 changes most likely to matter to employees who are approaching retirement:
The personal exemption remains at $0. The One, Big, Beautiful Bill Act made that change permanent.
Retirement account contributions: Pre-tax contributions to your employer's 401(k) plan may help reduce your taxable income. For 2027, employees can contribute up to $25,500 to 401(k), 403(b) and most 457 plans. Employees age 50 and over can add a catch-up contribution of up to $8,500, and employees age 60 through 63 may be able to make a higher catch-up of up to $11,750 if their plan allows it. If your 2026 Social Security wages from the employer sponsoring your plan were above $155,000, any 2027 catch-up contributions must be made as Roth (after-tax) contributions. The IRA contribution limit for 2027 is $7,500, plus a catch-up amount for those age 50 and over.
Charitable deduction for non-itemizers: Beginning with tax year 2026, taxpayers who take the standard deduction may deduct up to $1,000 ($2,000 joint) of cash gifts to eligible charities. Gifts to donor-advised funds and non-cash gifts do not qualify.
Child Tax Credit: For 2027, the Child Tax Credit is up to $2,300 per qualifying child. The credit begins to phase out above $200,000 ($400,000 joint) of modified adjusted gross income.
Remote work and state taxes: If you work remotely in a different state from your employer's office, you may owe tax in more than one state. Some states, including New York, apply a "convenience of the employer" rule that can tax a remote employee's wages as if the work were done in that state. A tax advisor can help you review whether credits or other options apply to your situation.
2027 Federal Income Tax Brackets
| Rate | Single | Married Filing Jointly | Married Filing Separately | Head of Household |
|---|---|---|---|---|
| 10% | $0 - $12,800 | $0 - $25,600 | $0 - $12,800 | $0 - $18,250 |
| 12% | $12,801 - $52,025 | $25,601 - $104,050 | $12,801 - $52,025 | $18,251 - $69,650 |
| 22% | $52,026 - $109,125 | $104,051 - $218,250 | $52,026 - $109,125 | $69,651 - $109,100 |
| 24% | $109,126 - $208,325 | $218,251 - $416,650 | $109,126 - $208,325 | $109,101 - $208,300 |
| 32% | $208,326 - $264,550 | $416,651 - $529,100 | $208,326 - $264,550 | $208,301 - $264,550 |
| 35% | $264,551 - $661,375 | $529,101 - $793,650 | $264,551 - $396,825 | $264,551 - $661,350 |
| 37% | $661,376+ | $793,651+ | $396,826+ | $661,351+ |
Source: IRS Rev. Proc. 2026-35, section 3.01, Tables 1-4 (IR-2026-133, November 5, 2026).
Inflation reduces purchasing power over time, so the same goods and services cost more as prices rise. Social Security benefits rise 3.6% in January 2027 through the annual cost-of-living adjustment. When building a retirement income plan, consider inflation assumptions, Medicare premiums, prescription drug costs and other health care expenses alongside the 2027 tax brackets and deductions above. For 2027, the standard Medicare Part B premium is $209.40 a month and the annual deductible is $292. The Part A inpatient hospital deductible is $1,776 per benefit period. Hospital coinsurance is $444 a day for days 61 through 90 and $888 a day for lifetime reserve days. Skilled nursing facility coinsurance is $222 a day for days 21 through 100. Out-of-pocket spending on covered Part D drugs is capped at $2,400.
Sources: IRS, Social Security Administration, Centers for Medicare & Medicaid Services.
No matter where you stand in the planning process, or your current age, we hope this guide provides you a good overview of the steps to take and resources that help you simplify your transition from your company into retirement and get the most from your benefits.
You know you need to be saving and investing, especially since time is on your side the sooner you start, but you don’t have the time or expertise to know if you’re building retirement savings that can last after leaving your company.
Source: Is it Worth the Money to Hire a Financial Advisor? The Balance, 2021
Starting to save as early as possible matters. Time on your side means compounding can have significant impacts on your future savings. And, once you’ve started, continuing to increase and make the most of your contributions for your 401(k) plan is key.
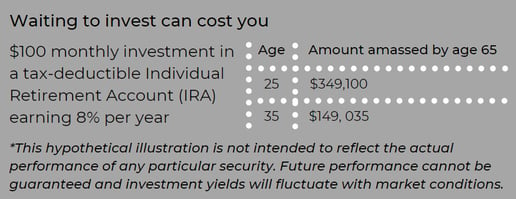
*Source: Bridging the Gap Between 401(k) Sponsors and Participants, T.Rowe Price, 2020
As decades go by, you’re likely full swing into your career at your company and your income probably reflects that. However, the challenges of saving for retirement start coming from large competing expenses: a mortgage, raising children, and saving for their college.
One of the classic planning conflicts is saving for retirement versus saving for college. Most financial planners will tell you that retirement from your company should be your top priority because your child can usually find support from financial aid while you’ll be on your own to fund your retirement.
How much we recommend that you invest towards your retirement is always based on your unique financial situation and goals. However, consider investing a minimum of 10% of your salary toward retirement through your 30s and 40s.
As you enter your 50s and 60s, you’re ideally at your peak earning years with some of your major expenses, such as a mortgage or child-rearing, behind you or soon to be in the rearview mirror. This can be a good time to consider whether you have the ability to boost your retirement savings goal to 20% or more of your income. For many people, this could potentially be the last opportunity to stash away funds.
In 2027, workers can contribute up to $25,500 into their retirement plan/401(k), and workers age 50 or older can add an additional $8,500 in catch-up contributions for a combined annual total of $34,000. Workers age 60 to 63 may be able to make a higher catch-up of $11,750 if their plan allows. These limits are adjusted annually for inflation.
These retirement savings vehicles give you the chance to take advantage of three main benefits:
UnitedHealth Group does not offer a traditional pension (defined benefit) plan to employees, so the lump-sum-versus-annuity discussion below applies only to a pension earned with another employer. Retirement savings are built primarily through the UnitedHealth Group 401(k) Savings Plan, along with the Executive Savings Plan for eligible senior management and executives.
UnitedHealth Group
Executive Saving Plan Overview
For UnitedHealth employees, understanding your retirement benefits is crucial. Whether you work at UnitedHealth, renowned for its commitment to healthcare innovation and service, or another company, your retirement plan is crafted to fit your career and dedication. Here’s an overview of the UnitedHealth retirement plan. Understanding these nuances will help you make informed decisions about your future.
The Executive Savings Plan (ESP) at UnitedHealth Group offers several benefits:
This guide offers an overview of the ESP, helping you understand how it works.
Eligibility: You can join the Plan if:
The Executive Vice President & Chief Human Resources Officer will only select employees who are part of a select group of management or highly compensated employees under ERISA.
Eligible Grade Level includes:
You can adjust your savings contributions once a year during the annual ESP enrollment period. If you enroll or make changes and later become ineligible (except for leaving the company), your contributions continue until year-end or until your incentive award is paid. Withdrawals due to 401(k) hardship or ESP unforeseen emergencies stop contributions immediately.
Proration for New Hires: New hires starting outside enrollment can defer a portion of their incentive award based on days left in the year after enrolling online. Awards earned this year for next year cannot be deferred into the 401(k).
Proration for Promotions: Promoted employees can defer incentive awards based on days left in the year after enrolling online. Awards earned this year for next year cannot be deferred into the 401(k).
During ESP enrollment, you can adjust deferral percentages or start/stop participation.

ESP Distribution
General Rule: When the employee stops working for the company (separation from service), the employer will start paying out the participant’s account. No application is needed, the account will automatically be paid out after the stop working for the company.
Distribution options are chosen the time of your enrollment. If you do not make a distribution election for your deferrals this year and you do not have a distribution election on file, your deferrals this year and associated matching and investment fund credits will be distributed from your account on January of the year following the year in which you separate from service or you become disabled, with payment made to you in February.
Post-Employment Distribution Options
Post-employment options begin paying out after you separate from service† with UnitedHealth Group. Refer to the following chart to learn about the five post-employment distribution options.

In Service Withdrawals:
There are two types of in-service distributions:

Making Changes to Your Distribution Elections
Once you have elected a form of distribution for your deferrals (and related Company matching and investment fund credits), you may not change your election to accelerate the payment. You may, however, change your distribution election one time and delay receipt of the payment for at least five years. Refer to the table below. Note that optional forms of distribution may change in future years.
Normal Distribution Options:

Retirees who are eligible for a pension are often offered the choice of receiving their pension payments for life, or receive a lump-sum amount all-at-once. The lump sum is the equivalent present value of the monthly pension income stream – with the idea that you could then take the money (rolling it over to an IRA), invest it, and generate your own cash flow by taking systematic withdrawals throughout your retirement years.
The upside of electing the monthly pension is that the payments are designed to continue for life (at least to the extent that the pension plan itself remains in place and solvent and doesn’t default). Thus, whether you live 10, 20, 30, or more years after retiring from your company, the monthly pension is designed to keep paying, which may help address the risk of outliving your income.
The major downside of the monthly pension are the early and untimely passing of the retiree and joint annuitant. This often translates into a reduction in the benefit or the pension ending altogether upon the passing. The other downside, it that, unlike Social Security, company pensions rarely contain a COLA (Cost of Living Allowance). As a result, with the dollar amount of monthly pension remaining the same throughout retirement, it will lose purchasing power when the rate of inflation increases.
In contrast, selecting the lump-sum gives you the potential to invest, earn more growth, and potentially generate even greater retirement cash flow. Additionally, if something happens to you, any unused account balance will be available to a surviving spouse or heirs. However, if you fail to invest the funds for sufficient growth, there’s a danger that the money could run out altogether and you may regret not having held onto the pension’s “income for life” feature.
Ultimately, the “risk” assessment that should be done to determine whether or not you should take the lump sum or the lifetime payments that your company pension offers, depends on what kind of return must be generated on that lump-sum to replicate the payments of the annuity. After all, if it would only take a return of 1% to 2% on that lump-sum to create the same monthly pension cash flow stream, there is less risk that you will outlive the lump-sum. However, if the pension payments can only be replaced with a higher and much riskier rate of return, there is, in turn, a greater risk those returns won’t manifest and you could run out of money.
Overview
The UnitedHealth Group 401(k) Savings Plan helps employees save for retirement through pre-tax and Roth contributions. It offers investment options and employer matching contributions to accelerate savings growth.
Eligibility
There is no waiting period. Employees can enroll in the Plan immediately at any time. Newly eligible employees, if no action is taken, will automatically be enrolled at a 3% pre-tax contribution rate.
Unless the employee declines or elects a different rate, that 3% default then increases automatically each year until the combined pre-tax and Roth contribution rate reaches 6% of pay.
Eligibility for UnitedHealth's matching contribution requires one year of service; before reaching one year, an employee's own contributions are not yet eligible to be matched.
Vesting
Employees are fully vested in their own contributions (pre-tax and Roth) at all times. Employer matching contributions become 100% vested after completing two years of service.
Contributions
Participants can contribute up to 80% of their eligible pay into pre-tax and/or Roth 401(k) accounts, subject to IRS annual limits. The company matches 100% of the first 1% of eligible pay plus 50% of the next 5%, up to 3.5% of eligible pay; to receive the full match, participants must contribute at least 6% of their pay per pay period.
Withdrawals
Withdrawals are allowed upon termination of employment, retirement, reaching age 59½, or experiencing severe financial hardship defined by the Plan. Participants can withdraw contributions and earnings or leave them in the Plan until required minimum distributions begin (age 73, or 75 if born in 1960 or later) if the balance exceeds $1,000.
Loans
Participants can take loans from their 401(k) account for various purposes. More information and loan requests can be managed through NetBenefits platform or by contacting the benefits department.
Death & Beneficiaries
Participants can designate beneficiaries through Fidelity’s Online Beneficiary Service. This service allows for easy designation updates and verification online. Upon death, the designated beneficiaries receive the participant’s account balance.
This plan provides flexibility and options for employees to save and invest for retirement while receiving employer contributions that help grow their retirement savings faster. It emphasizes ease of use through online management tools and helps participants stay informed about their options and benefits.
Over half of plan participants admit they don’t have the time, interest or knowledge needed to manage their 401(k) portfolio. But the benefits of getting help goes beyond convenience. Getting help may make it easier to build a diversified portfolio and stick with it through market swings. 
Getting help can be the key to better results across the 401(k) board.
A 2010 Charles Schwab study found several positive outcomes common to those using independent professional advice. They include:
Rolling Over Your 401(k)
When you qualify for a distribution, you have three options:
How does Net Unrealized Appreciation work?
First an employee must be eligible for a distribution from their qualified company-sponsored plan. Generally, at retirement or age 59 1⁄2, the employee takes a 'lump-sum' distribution from the plan, distributing all assets from the plan within one tax (calendar) year. The portion of the plan that is made up of mutual funds and other investments can be rolled into an IRA for further tax deferral. The highly appreciated company stock is then transferred to a non-retirement account.
The tax benefit comes when you transfer the company stock from a tax-deferred account to a taxable account. At this time, you apply NUA and you incur an ordinary income tax liability on only the cost basis of your stock. The appreciated value of the stock above its basis is not taxed at the higher ordinary income tax but at long-term capital gains rates of 0%, 15%, or 20%, depending on your taxable income. Depending on your tax brackets, this could mean meaningful tax savings on the appreciation.
You may be interested in learning more about NUA with a complimentary one-on-one session with a financial advisor from The Retirement Group.
When you qualify for a distribution, you have three options:
Your retirement assets may consist of several retirement accounts: IRAs, 401(k)s, taxable accounts, and others.
So, what is the most efficient way to take your retirement income after leaving your company?
You may want to consider meeting your income needs in retirement by first drawing down taxable accounts rather than tax-deferred accounts.
This may help your retirement assets with your company last longer as they continue to potentially grow tax deferred.
You will also need to plan to take the required minimum distributions (RMDs) from any company-sponsored retirement plans and traditional or rollover IRA accounts.
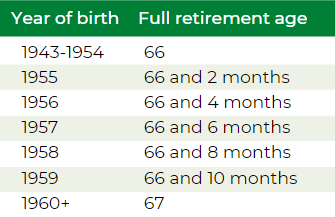
IRS rules require you to begin taking distributions from these types of accounts when you reach your RMD age: 73 if you were born from 1951 through 1959, or 75 if you were born in 1960 or later. Beginning in 2023, the excise tax for every dollar of your RMD under-distributed was reduced from 50% to 25%, and it may be 10% if the shortfall is corrected in time.
Current rules allow account owners to delay taking their first RMD until April 1 following the later of the calendar year they reach RMD age or, in a workplace retirement plan, retire.
Two flexible distribution options for your IRA
When you need to draw on your IRA for income or take your RMDs, you have a few choices. Regardless of what you choose, IRA distributions are subject to income taxes and may be subject to penalties and other conditions if you’re under 59½.
Partial withdrawals: Withdraw any amount from your IRA at any time. If you’re 73 or over, you’ll have to take at least enough from one or more IRAs to meet your annual RMD.
Systematic withdrawal plans: Structure regular, automatic withdrawals from your IRA by choosing the amount and frequency to meet your income needs after retiring from your company. If you’re under 59½, you may be subject to a 10% early withdrawal penalty (unless your withdrawal plan meets Code Section 72(t) rules).
Your tax advisor can help you understand distribution options, determine RMD requirements, calculate RMDs, and set up a systematic withdrawal plan.
HSA's
Health Savings Accounts (HSAs) are often celebrated for their utility in managing healthcare expenses, particularly for those with high-deductible health plans. However, their benefits extend beyond medical cost management, positioning HSAs as a potentially superior retirement savings vehicle compared to traditional retirement plans like 401(k)s, especially after employer matching contributions are maxed out.
Understanding HSAs
HSAs are tax-advantaged accounts designed for individuals with high-deductible health insurance plans. For 2027, the IRS defines high-deductible plans as those with a minimum deductible of $1,750 for individuals and $3,500 for families. HSAs allow pre-tax contributions, tax-free growth of investments, and tax-free withdrawals for qualified medical expenses—making them a triple-tax-advantaged account.
The annual contribution limits for HSAs in 2027 are $4,500 for individuals and $9,000 for families, with an additional $1,000 allowed for those aged 55 and older. Unlike Flexible Spending Accounts (FSAs), HSA funds do not expire at the end of the year; they accumulate and can be carried over indefinitely.
Comparing HSAs to 401(k)s Post-Matching
Once an employer's maximum match in a 401(k) is reached, further contributions yield diminished immediate financial benefits. This is where HSAs can become a strategic complement. While 401(k)s offer tax-deferred growth and tax-deductible contributions, their withdrawals are taxable. HSAs, in contrast, provide tax-free withdrawals for medical expenses, which are a significant portion of retirement costs.
HSA as a Retirement Tool
Post age 65, the HSA flexes its muscles as a robust retirement tool. Funds can be withdrawn for any purpose, subject only to regular income tax if used for non-medical expenses. This flexibility is akin to that of traditional retirement accounts, but with the added advantage of tax-free withdrawals for medical costs—a significant benefit given the rising healthcare expenses in retirement.
Furthermore, HSAs do not have Required Minimum Distributions (RMDs), unlike 401(k)s and Traditional IRAs, offering more control over tax planning in retirement. This makes HSAs particularly advantageous for those who might not need to tap into their savings immediately at retirement or who want to manage their taxable income.
Investment Strategy for HSAs
Initially, it's prudent to invest conservatively within an HSA, focusing on maintaining sufficient liquid funds to cover near-term deductible and other out-of-pocket medical expenses. However, once a financial cushion is established, treating the HSA like a retirement account by investing in a diversified mix of stocks and bonds can help enhance the account's growth potential over the long term.
Utilizing HSAs in Retirement
In retirement, HSAs can cover a range of expenses:
Conclusion
In summary, HSAs offer unique advantages that can make them a superior option for retirement savings, particularly once you are contributing enough to receive the full 401(k) match. Their flexibility in fund usage, coupled with tax advantages, makes HSAs an essential component of a comprehensive retirement strategy. By strategically managing contributions and withdrawals, individuals can work toward stronger financial health in retirement and help preserve both their medical and financial well-being.

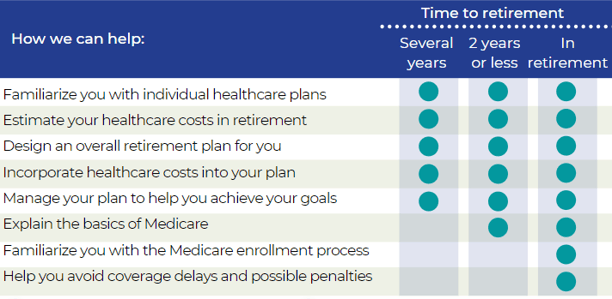
UnitedHealth Group also sponsors a group Medicare Advantage plan, the UnitedHealthcare Group Medicare Advantage (PPO) Plan, which had 855 participants at the end of 2025 according to its Form 5500 filing. Check with UnitedHealth Group's benefits center whether you would be eligible for it when you retire.
Divorce doesn’t disqualify you from survivor benefits. You can claim a divorced spouse’s survivor benefit if the following are true:
In the process of divorcing?
If your divorce isn’t final before your retirement date from your company, you’re still considered married. You have two options:
Source: The Retirement Group, “Retirement Plans - Benefits and Savings,” U.S. Department of Labor, 2019; “Generating Income That Will Last Throughout Retirement,” Fidelity, 2019
In the unfortunate event that you aren’t able to collect your benefits from your company, your survivor will be responsible for taking action.
What your survivor needs to do:
If you have a joint pension:
If your survivor has medical coverage through your company:
https://www.irs.gov/newsroom/irs-provides-tax-inflation-adjustments-for-tax-year-2022
https://news.yahoo.com/taxes-2022-important-changes-to-know-164333287.html
https://www.nerdwallet.com/article/taxes/federal-income-tax-brackets
https://www.the-sun.com/money/4490094/key-tax-changes-for-2022/
https://www.bankrate.com/taxes/child-tax-credit-2022-what-to-know/